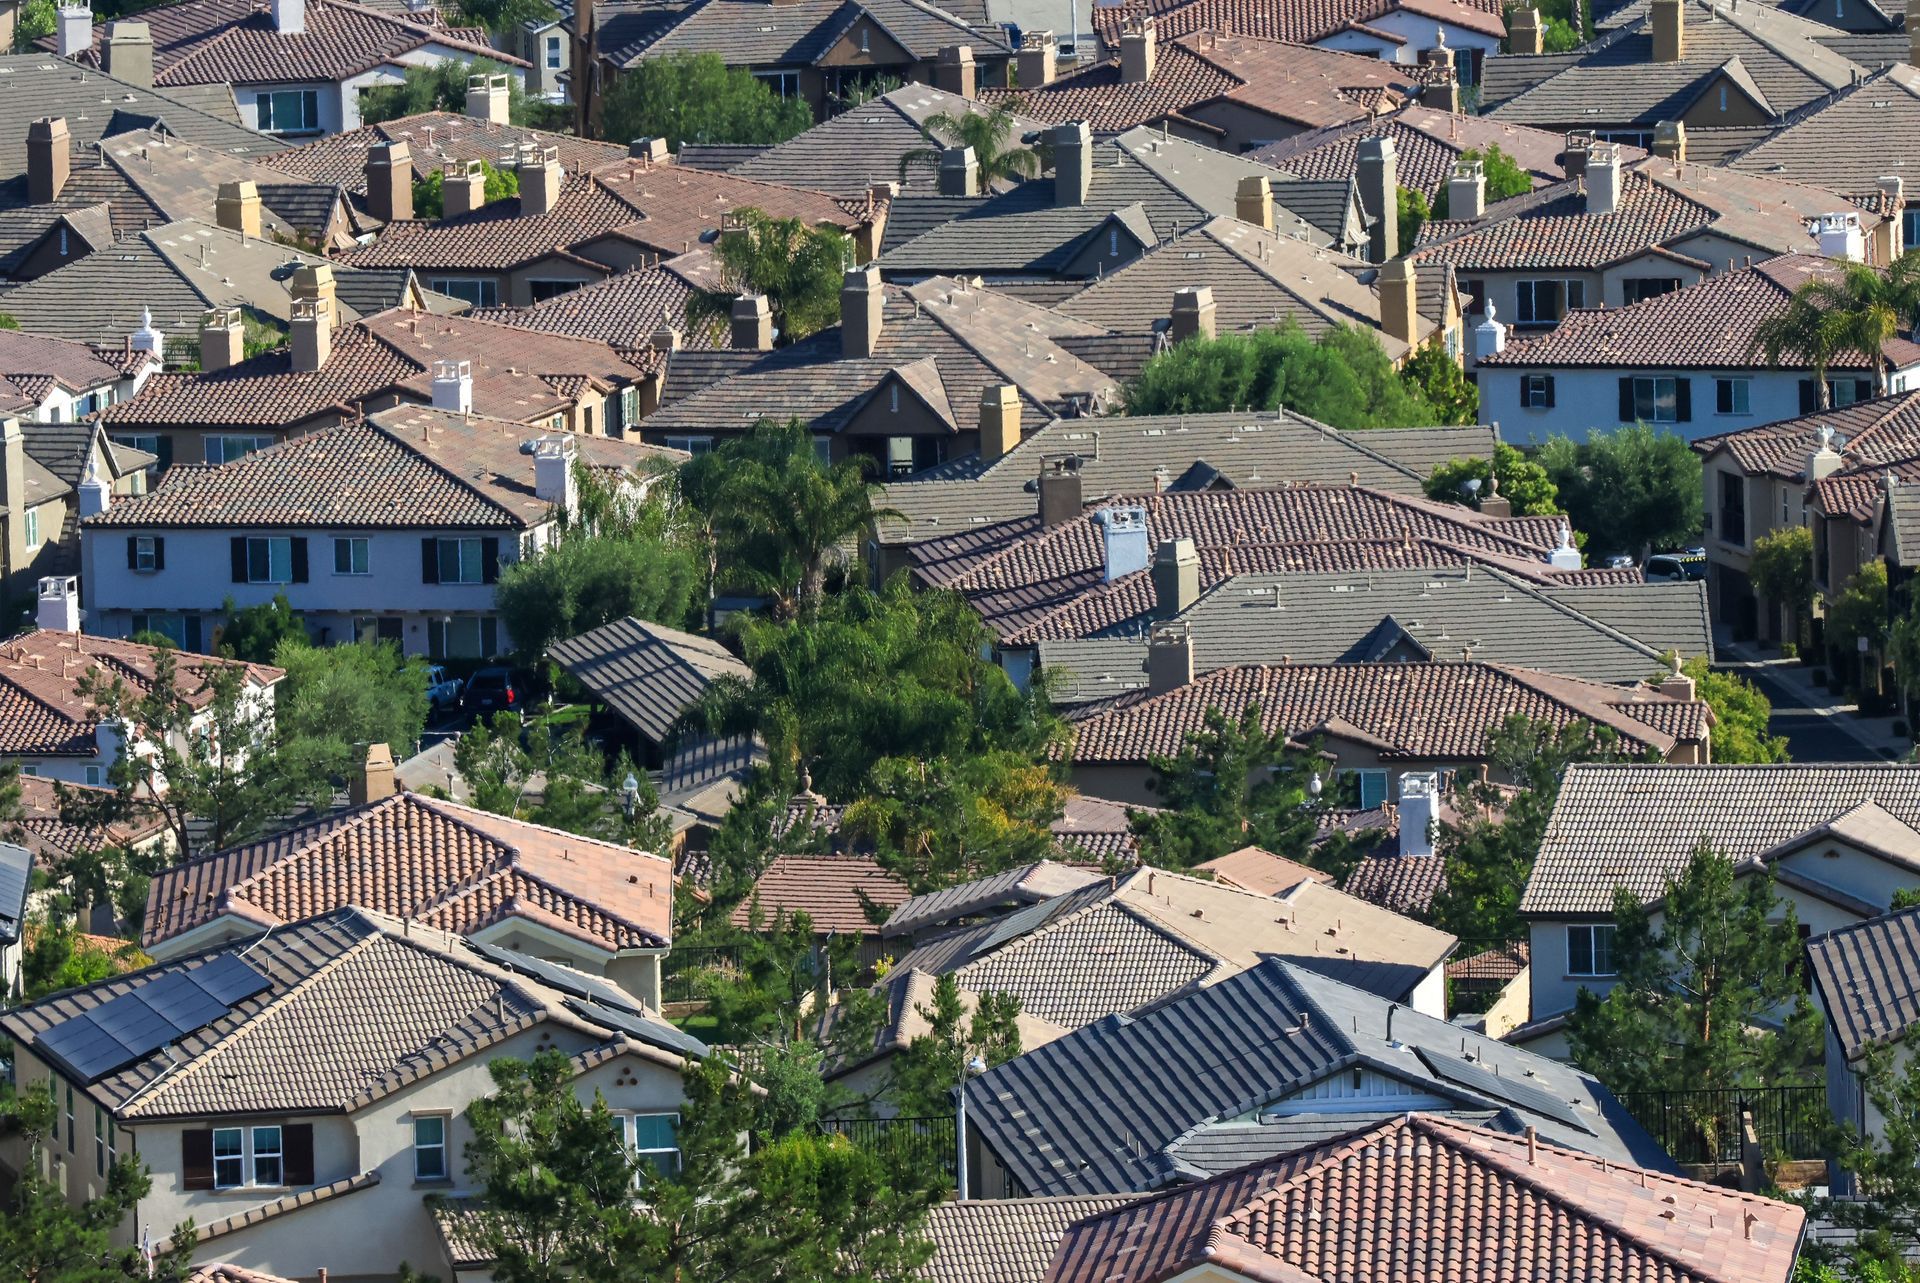
Queen Creek is not one housing market. There are the newer HOA tracts along Ellsworth and Rittenhouse, the acreage and horse properties out toward Ocotillo and Combs, and the stretch of town that sits in Pinal County instead of Maricopa. A home insurance quote that fits one of those does not automatically fit the others.
Riseson Insurance is an independent Arizona broker. We work for you, not for one carrier. Here is what actually drives home insurance in Queen Creek, what a standard policy leaves out, and why two houses a mile apart can come back quoted far apart.
Why Queen Creek homeowners need coverage that matches the address
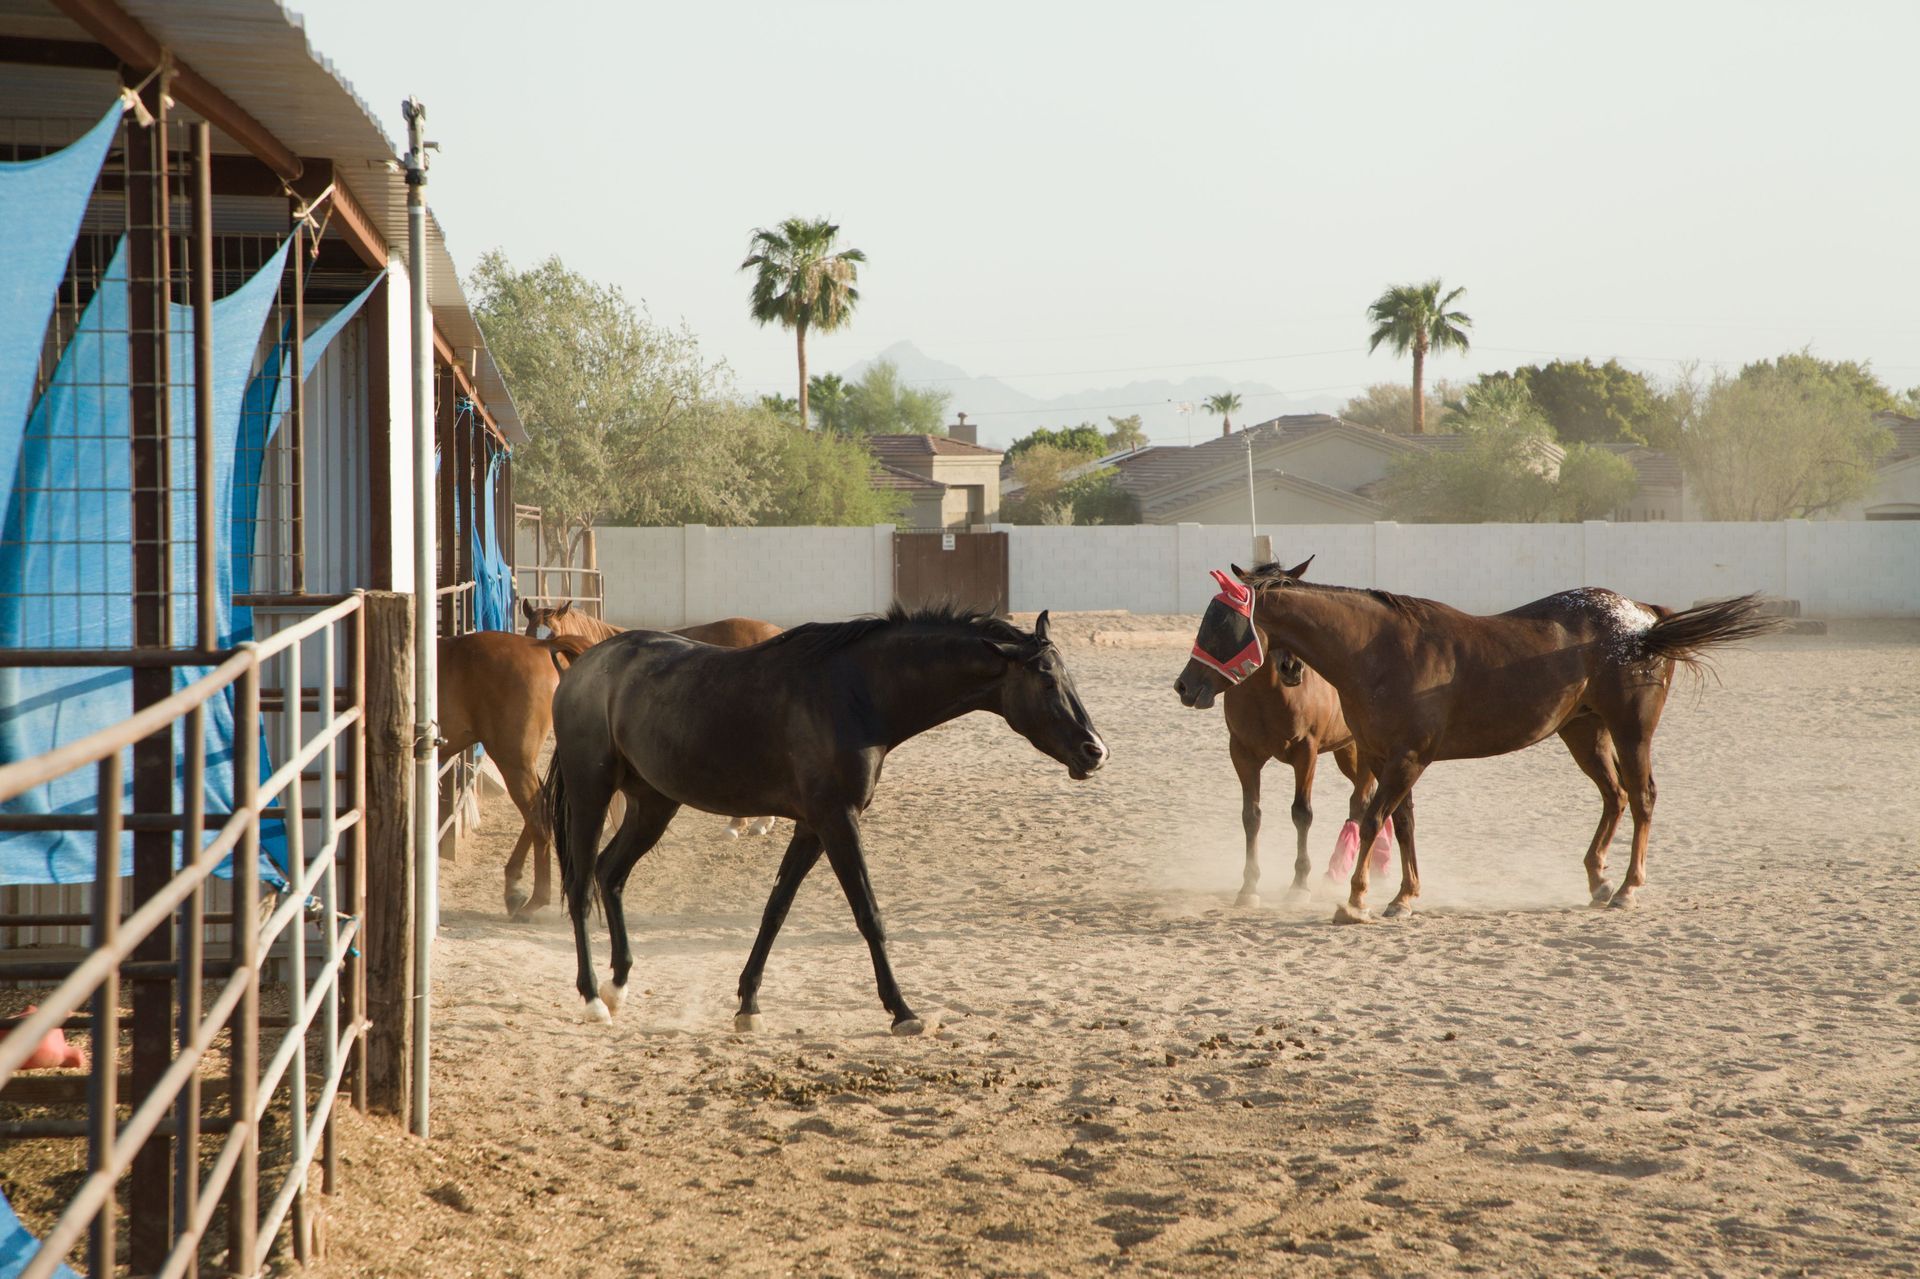
Queen Creek has grown fast, and carriers price that growth in two different ways. A recently built tract home is often easier to quote: newer roof, current building code, HOA maintenance rules. A custom acreage property is a different file. Barns, arenas, fencing, well equipment, and outbuildings may need to be scheduled, not assumed.
The monsoon pattern is the same across the East Valley, but the drainage is not. Hard desert ground sheds water quickly. Town floodplain materials describe special flood hazard areas as generally limited to Queen Creek Wash, Sonoqui Wash, pockets north of the Union Pacific line, and areas south of Hunt Highway (Town of Queen Creek floodplain ordinance staff report). Your parcel is either in that footprint or it is not. Guessing from a neighbor's experience is how people end up uninsured for the wrong peril.
Heat is the slower problem. Sustained summer temperatures age underlayment, HVAC, and stucco. On a new build that may not matter for a few years. On an older ranch parcel, roof age is often the item that changes the rate, or whether the carrier will write the risk at all.
How an independent broker shops Queen Creek home insurance
A captive agent represents one company. An independent broker compares more than one. For a Queen Creek address that usually means pulling the same dwelling limit, deductible, and liability across several top-rated carriers and looking for the
bundling angle, most often home plus auto, that actually lowers the total.
Sometimes the lowest home quote and the lowest auto quote live at different companies. We run both the bundled and the split versions and tell you which one wins. That is the job. It is not a slogan.
If you have not compared Queen Creek home insurance in the last year, you are comparing your current bill to itself. That is not a market check.
What home insurance costs in Queen Creek, AZ
There is no honest Queen Creek-only average published in the sources we use. The statewide figure is the right starting point, then your address moves it.
Arizona homeowners pay an average of $2,318 per year for a policy with $300,000 in dwelling coverage, $100,000 in liability, and a $1,000 deductible (Insure.com, average homeowners insurance cost in Arizona). Raise liability to $300,000 on that same dwelling and deductible and the statewide average is $2,344 a year (Insure.com).
The spread between companies is larger than most people expect. On the $300,000 dwelling / $100,000 liability / $1,000 deductible profile, Insure.com's Arizona company averages run from $1,456 a year to $2,948 a year. That is a gap of nearly $1,500 a year on paper-identical coverage.
Rates have also moved. Insure.com shows the Arizona average going from $2,122 in 2023 to $2,318 in 2025, about a 9% increase over that stretch. If a Queen Creek policy has auto-renewed for several years without a look, the odds are good you are no longer looking at a competitive number, or at a dwelling limit that still matches rebuild cost.
Newer construction can price better than older stock. Acreage, horses, and extra structures can price worse. Your quote will follow the file, not the town slogan.
Monsoon, wash flooding, and the two-county problem
From July through September,
monsoon storms bring microbursts, blowing dust, and short, heavy rain. The claim pattern in the East Valley is familiar: lifted or cracked roof tiles, water under flashing, downed block fencing, shade structures torn loose. A lot of it does not show up until a ceiling stain appears later.
Queen Creek also sits in two counties. The town has had to maintain separate floodplain rules for the Maricopa side and the Pinal side (Town of Queen Creek floodplain ordinance updates). That does not change how a homeowners policy reads, but it does change which flood maps and local drainage rules apply to the lot. Confirm the county before you assume a map from a Mesa or Gilbert neighbor applies.
Flood is a separate policy. A standard homeowners policy does not cover flood damage (FloodSmart.gov;
Maricopa County Flood Control). Maricopa County notes that 1 in 4 flood insurance claims come from outside a mapped floodplain (ready.maricopa.gov). An NFIP policy generally takes effect 30 days after purchase, with narrow exceptions such as buying in connection with a mortgage (FloodSmart.gov). Deciding you want flood coverage when a storm is on the forecast is usually 30 days too late.
NFIP building coverage for a home is capped at $250,000 and contents at $100,000 (FloodSmart.gov). Those caps are a reason some households price private flood alongside NFIP. That is a quote conversation, not a one-line answer.
What a standard Queen Creek policy does not cover
Flood, as above. Wear and tear. Damage from a roof that was already at the end of its life. Detached structures and farm or horse equipment that were never listed. A dwelling limit that was set to last year's rebuild cost, or to the purchase price, which is the wrong number.
You insure for the
cost to rebuild, not the market value, and not the land. In a town with a lot of new construction, labor and materials can move faster than the limit on an auto-renewed policy. That is one of the first things we check on a Queen Creek review.
If you have a barn, arena, or well equipment, say so up front. Those items are easy to miss on a standard HO-3 and expensive to discover after a loss. A licensed agent has to verify what is and is not on the form. This article is not that review.
Frequently asked questions about home insurance in Queen Creek, AZ
How much does home insurance cost in Queen Creek, AZ? Start from the Arizona average of $2,318 per year for $300,000 dwelling, $100,000 liability, and a $1,000 deductible (Insure.com). Queen Creek new builds often sit in a different band than older acreage. Roof age, claims history, and extra structures move the number more than the town name does.
Does home insurance cover monsoon damage in Queen Creek? Wind and hail from a monsoon storm are generally considered under a standard policy, subject to your deductible and any separate wind or hail deductible. Gradual wear, deferred maintenance, and damage traced to a roof that was already worn out are the usual exclusions. Document roof condition before storm season.
Is flood insurance included? No. Standard homeowners policies exclude flood. Queen Creek parcels near Queen Creek Wash or Sonoqui Wash should price a separate NFIP or private flood policy early, because NFIP coverage typically waits 30 days (FloodSmart.gov).
Should I insure my Queen Creek home for what I paid for it? No. You insure for rebuild cost, which excludes the land and can be higher or lower than the sale price. In a fast-building East Valley town, an outdated dwelling limit is a common problem on policies that have not been reviewed.
Does it matter that part of Queen Creek is in Pinal County? For flood maps and local drainage rules, yes. For shopping carriers, we still quote the actual address. Do not borrow a Mesa or Gilbert assumption and paste it onto a Pinal parcel.
Get your Queen Creek home insurance quote today
If you own a home in Queen Creek and have not compared home insurance in the last year, you are likely overpaying, underinsured on rebuild cost, or both. Riseson Insurance is an independent Arizona broker, which means we work for you, not for one company. We will pull quotes from multiple top-rated carriers, walk through what is actually covered, and find the bundling angle that saves the most. Neighboring East Valley homeowners can also see our
Mesa home insurance guide. Reach out and we will put your Queen Creek options in one place.