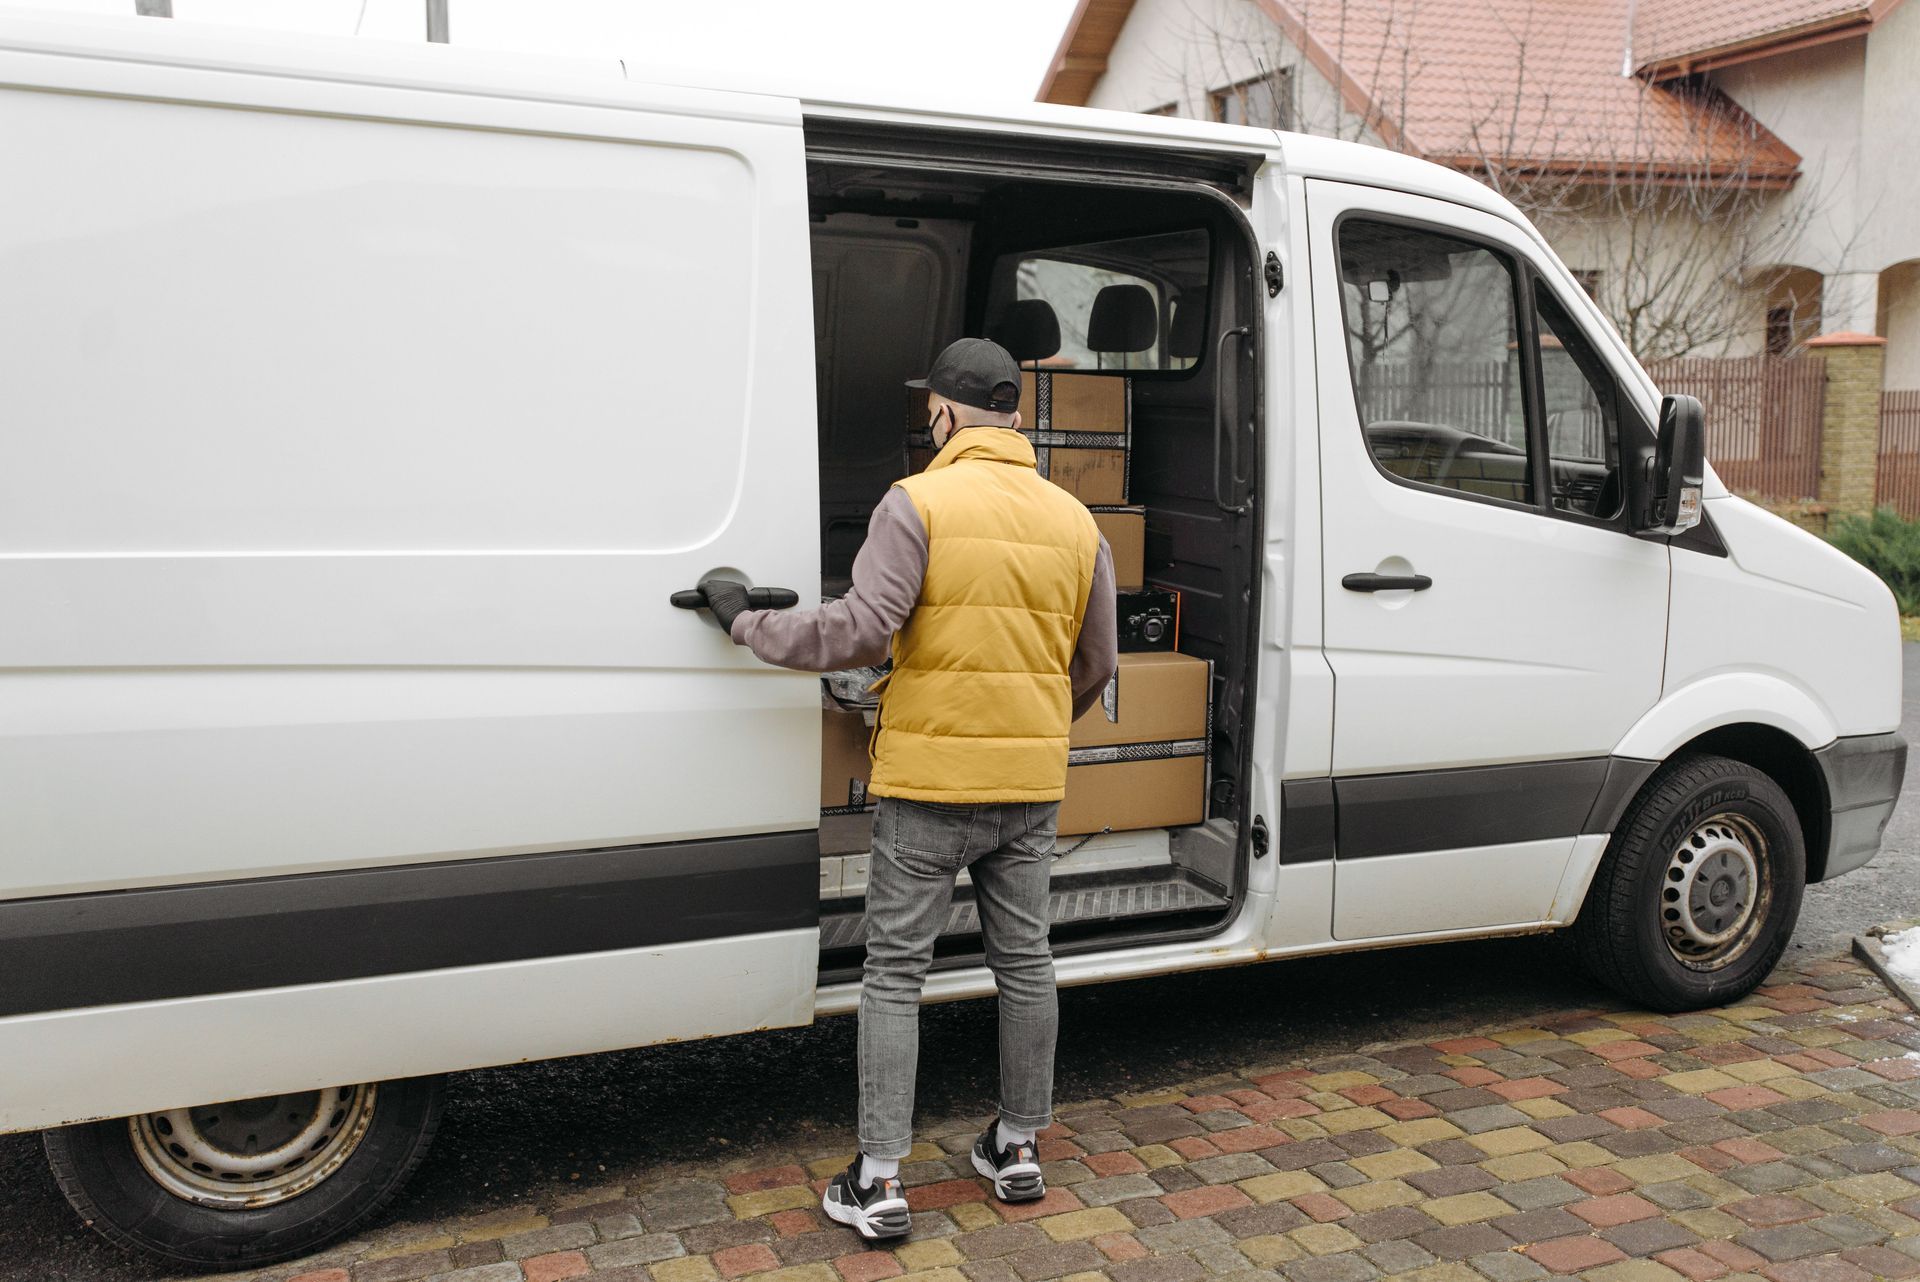
If your Arizona business runs two or more vehicles, you already know how much rides on them. Vans, pickups, box trucks and service rigs carry your crew, your tools and your reputation across the Valley every day, and one bad afternoon on the Loop 101 can put all of it at risk.
Fleet insurance in Arizona brings every business vehicle and every driver under one commercial auto policy. This guide covers what fleet coverage includes, what it costs, what Arizona requires, and how an independent broker can help you shop it across several carriers at once.
Why Arizona businesses need fleet insurance
Personal auto policies usually exclude vehicles used for business, and that gap gets wider as your fleet grows. Progressive Commercial notes that many of Arizona's 706,000 small businesses need commercial auto coverage because work vehicles face more risk than personal cars (Progressive Commercial).
Landscapers in Gilbert, HVAC contractors in Mesa, delivery operators in Phoenix and property managers in Scottsdale all share the same exposure. More vehicles on the road means more miles, more drivers and more chances for a claim that lands on your business, not just on one driver.
A fleet policy also keeps administration simple. Instead of juggling separate renewal dates and ID cards, you add or remove vehicles and drivers on one policy as your business changes.
What fleet insurance covers
Most Arizona fleet policies are built from the same core pieces as a commercial auto policy, with limits set for the whole operation. Liability pays for injuries and property damage you cause to others. Collision and comprehensive cover your own vehicles after a crash, theft, hail or a monsoon dust storm.
From there, you can add coverage that fits your work. Common options include uninsured and underinsured motorist coverage, medical payments, hired and non-owned auto liability for employees who drive their own cars on company errands, rental reimbursement to keep jobs moving while a truck is in the shop, and coverage for permanently attached equipment like ladder racks or lift gates.
If you want a refresher on the building blocks, our guide to
commercial auto insurance walks through each coverage in plain language.
How much does fleet insurance cost in Arizona
Fleet pricing depends on what you drive and how you use it. Progressive Commercial reports that in 2025 its national average monthly cost was $260 for contractors and $276 for business auto customers (Progressive Commercial). Your fleet total scales with the number and type of vehicles you insure.
The biggest rating factors are your industry, vehicle size and weight, driver records, where the vehicles are garaged and how far they travel. A fleet that stays inside Tempe city limits usually rates lower than one running routes from Phoenix to Tucson and Flagstaff. Higher liability limits, such as a $1 million combined single limit, cost more than state minimums but protect your business far better.
You can often lower cost by keeping motor vehicle records clean, adding telematics or dash cameras, choosing a higher deductible on physical damage, and bundling the fleet with your general liability or business owners policy.
Arizona fleet insurance requirements
Arizona requires liability insurance on every registered vehicle, with minimums of $25,000 per person and $50,000 per accident for bodily injury, plus $15,000 for property damage (ADOT MVD). Those 25/50/15 limits apply to commercial vehicles too, but they are a floor, not a recommendation for a business.
Some vehicles face stricter rules. ADOT sets higher minimums for taxis, livery vehicles and limousines, and the Federal Motor Carrier Safety Administration typically requires large interstate vehicles like semi trucks to carry at least $750,000 in combined single limit liability (Progressive Commercial). Many commercial contracts and general contractors also require $1 million limits before you can start a job.
Arizona is an at-fault state, so the business whose driver causes a crash pays for the damage. With serious injury claims easily topping state minimums, most fleet owners choose limits well above 25/50/15.
How an independent broker helps your fleet
Fleet coverage is not one size fits all, and carriers differ a lot in how they price industries, vehicle types and driver histories. As an independent Arizona broker, Riseson Insurance shops your fleet with multiple carriers so you can compare price and coverage side by side.
We also look at the full picture. A fleet policy pairs naturally with
business interruption insurance and solid
liability coverage, so one accident does not stall your operations or reach your business assets.
Frequently asked questions
How many vehicles do I need for fleet insurance in Arizona? Many carriers treat two or more business vehicles as a fleet, though the threshold varies by insurer. An independent broker can tell you which carriers give the best terms for your fleet size.
What are the minimum insurance requirements for business vehicles in Arizona? Arizona requires at least $25,000 per person and $50,000 per accident for bodily injury, plus $15,000 for property damage, per ADOT. Interstate trucks under FMCSA rules typically need at least $750,000 in liability. Most businesses carry much higher limits to protect their assets.
Does fleet insurance cover employees driving their own cars for work? Not automatically. Hired and non-owned auto liability is the coverage that protects your business when employees use personal or rented vehicles for company errands. It can usually be added to a fleet or commercial auto policy.
How much does commercial auto insurance cost for an Arizona fleet? Progressive Commercial reports national 2025 averages of about $260 a month for contractors and $276 a month for business auto customers. Your Arizona fleet total depends on vehicle type, driver records, location and limits. Comparing several carriers is the most reliable way to find a fair price.
Get your fleet insurance quote today
If your business runs two or more vehicles in Arizona and you have not compared fleet insurance quotes in the last year, you are likely overpaying or underinsured. Riseson Insurance is an independent Arizona broker, which means we work for you, not for one carrier. We will pull quotes from multiple top-rated companies, walk you through what is actually covered, and find the bundling angle that saves the most. Reach out for a free Arizona fleet insurance quote and see your options in one place.