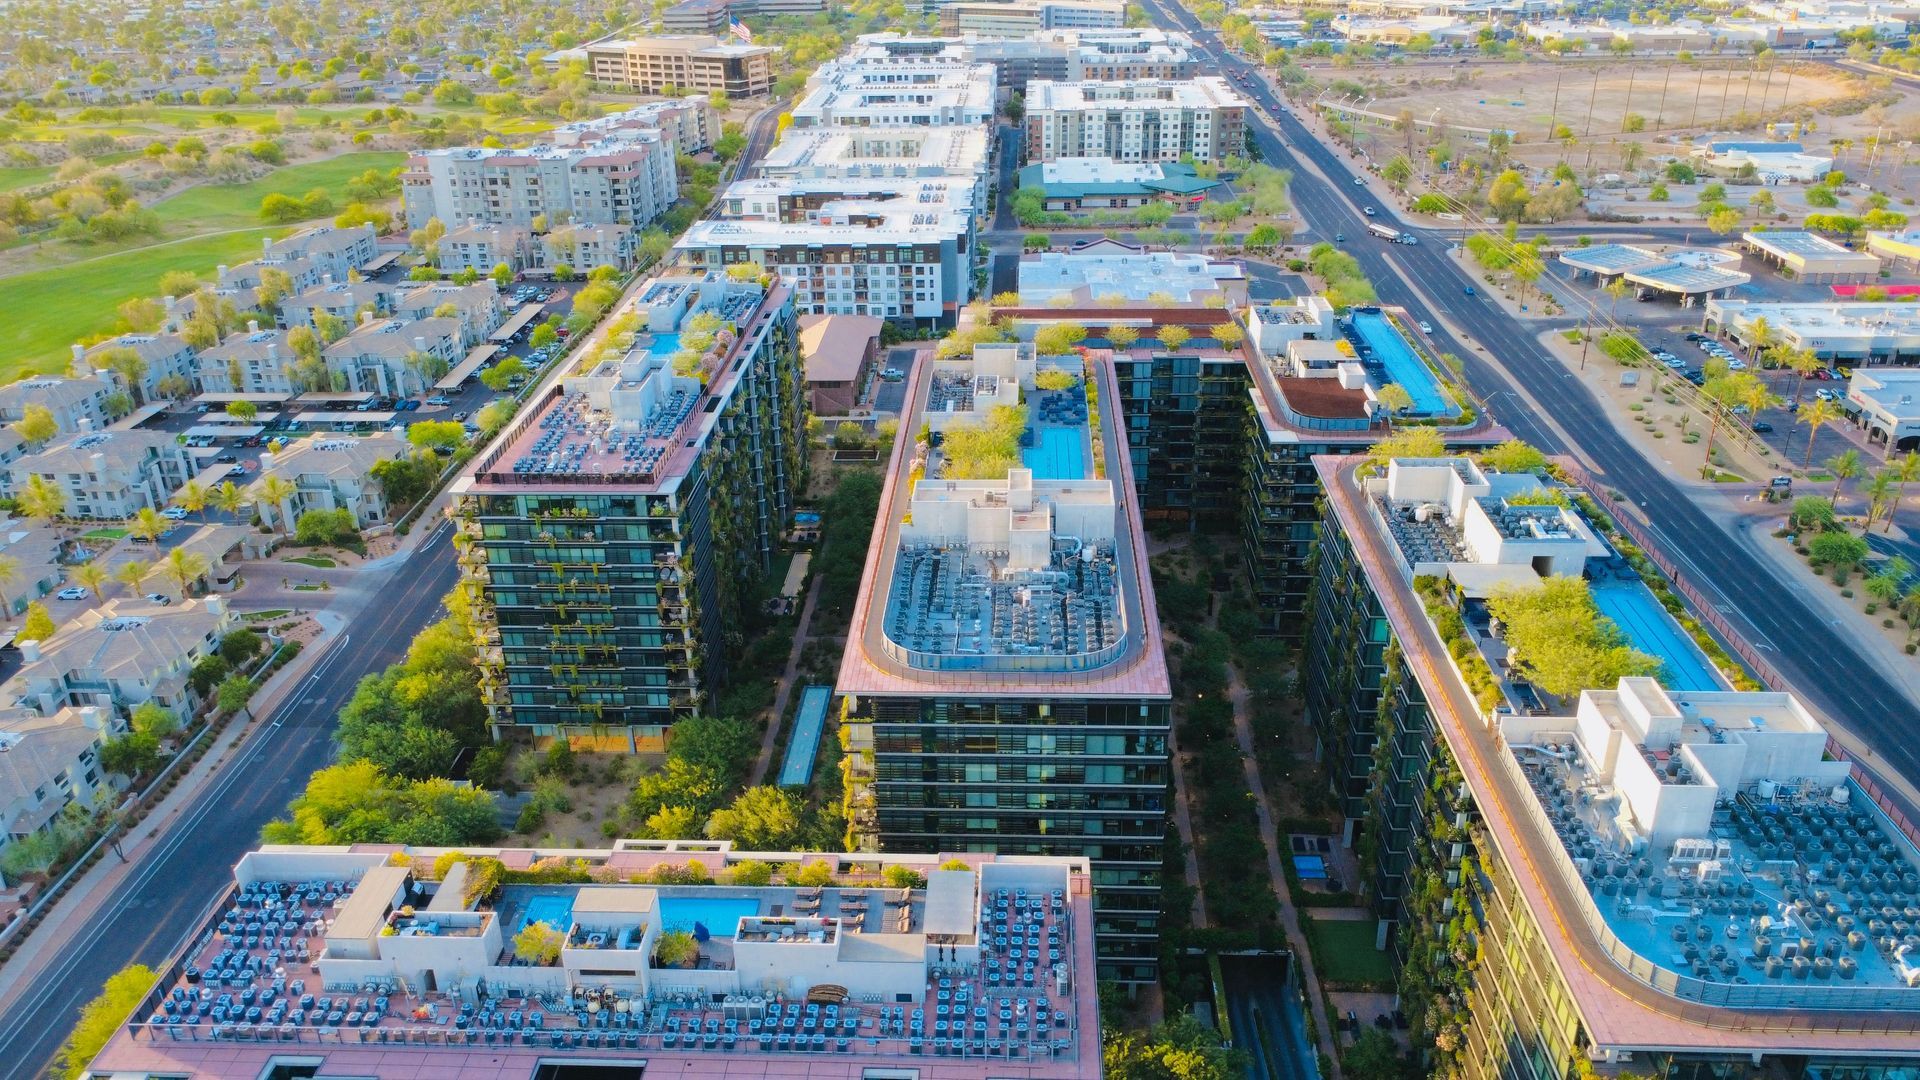
Mesa is the third largest city in Arizona and one of the most owner heavy cities in the East Valley. About 64.4% of occupied housing units in Mesa are lived in by their owners, according to
Data USA's Census profile for the city. That is roughly two out of every three households carrying the full financial weight of a house.
If you own one of them, your home insurance policy is the single document standing between a bad monsoon night and a rebuild you pay for yourself. Most Mesa homeowners bought that policy once, at closing, and have not looked at it since. This guide walks through what home insurance in Mesa actually costs, what the standard policy leaves out, and how an independent broker shops it differently.
Why Mesa homeowners need more than a lender required policy
Arizona does not require homeowners insurance by law. Your mortgage lender does, and that requirement is the reason most Mesa policies exist. The problem is that a lender only cares about the loan balance, not about whether you could rebuild.
Mesa housing stock spans a wide range. There are 1970s and 1980s ranch homes near Main Street and Dobson Ranch with original wiring and aging plumbing, and there is newer construction pushing east toward Gateway and Eastmark. Those two homes carry different risks and should not carry the same policy.
Age of the home is one of the biggest rate drivers insurers look at.
Insure.com notes that an older home with original electrical systems can cost 20% to 40% more to insure than comparable new construction. If you have already replaced the roof, the panel, or the water heater, that is worth telling your carrier, because it can pull the number back down.
What home insurance costs in Mesa and what drives the number
Homeowners in Mesa pay an average of $2,390 per year for a standard policy with $300,000 in dwelling coverage, $100,000 in liability, and a $1,000 deductible, according to
Insure.com's 2025 Mesa rate data. That is $125 below the national average of $2,515 for the same coverage profile.
Coverage level moves the number more than anything else you control. The same data shows a $200,000 dwelling limit averaging $1,852 per year in Mesa, so stepping up to $300,000 adds about $538 annually. Carrier choice moves it just as much. Insure.com puts State Farm lowest in Mesa at an average of $1,486 per year, with other national carriers in the same city ranging up past $2,800.
That spread is the whole argument for shopping. Two Mesa homeowners on the same street, with the same house and the same claims history, can pay a four figure difference simply because of which company wrote the policy.
Monsoon season, flood exclusions, and the gap most Mesa policies leave open
Mesa sits in the middle of Arizona's monsoon corridor. From roughly July through September, microbursts drive wind, blowing dust, hail, and sheeting rain across the East Valley in short violent bursts. Wind and hail damage to your roof is generally a covered peril. Water that rises off the ground and enters the house is not.
That distinction catches people.
The National Flood Insurance Program is direct about it: most homeowners and renters policies do not cover flood damage at all. NFIP also reports that from 2014 through 2024, almost one third of its flood claims came from properties outside designated high risk flood areas.
Mesa has plenty of that profile. Homes near the Consolidated Canal, along the Salt River corridor, or at the low end of a neighborhood's drainage can take water during a monsoon burst without ever sitting in a mapped high risk zone. If you are in one of those spots, a separate flood policy is worth pricing. Our guide to
preparing for monsoon season covers the maintenance side of the same problem.
Bundling home and auto in Mesa
Bundling is the most reliable discount available to a Mesa homeowner. Insure.com puts the multi policy discount range at 10% to 25% when home and auto sit with the same carrier. On a $2,390 home premium, the low end of that range alone is roughly $239 a year, before the auto side savings.
Mesa makes this especially practical because most households here drive. The Loop 202 Red Mountain, US 60, and Loop 101 commutes put real annual mileage on East Valley cars, and auto premiums here are not small. Our breakdown of
how much you save bundling home and auto in Arizona goes through the math, and our
Mesa car insurance guide covers the auto half in detail.
One caution. Bundling is only a win when both halves are competitively priced. Some carriers advertise a large bundle discount off an already high base rate. That is a comparison an independent broker can run for you in one sitting.
How an independent broker changes the Mesa shopping process
Riseson Insurance is an independent Arizona broker. We are not captive to one company, which means we are not trying to fit your Mesa home into a single carrier's underwriting box. We quote it across multiple top rated companies and bring back the comparison.
That matters most on the homes carriers get picky about. Older Mesa roofs, homes with a pool and no fence sensor, properties with a prior water claim on the CLUE report, and manufactured homes in the many Mesa parks all get treated differently company to company. A captive agent has one answer. We have several.
We also live here. We know which Mesa neighborhoods flood, which ones have older service panels, and which carriers have been reasonable on East Valley monsoon roof claims.
Coverage Mesa homeowners often skip
Replacement cost on the dwelling, not actual cash value, is the one to get right. Actual cash value depreciates your roof before it pays you, which is a painful surprise after a hailstorm. Our explainer on
replacement cost insurance walks through the difference.
Beyond that, three add ons come up constantly in Mesa: water backup coverage for sewer and drain events, extended or guaranteed replacement cost to absorb construction cost inflation, and higher personal liability limits if you have a pool, a trampoline, or a dog. Liability at $100,000 is the default on most policies and is low for a homeowner with equity to protect.
Frequently asked questions
How much does home insurance cost in Mesa, AZ?
Homeowners in Mesa average $2,390 per year for $300,000 in dwelling coverage, $100,000 in liability, and a $1,000 deductible, per Insure.com's 2025 rate data. That is $125 under the $2,515 national average for the same coverage. Your own number depends on the home's age, size, roof condition, coverage limits, and claims history.
Is homeowners insurance required in Arizona?
No Arizona law requires it. Nearly every mortgage lender does require it as a condition of the loan, and if you own the home outright you can legally go without. Doing so means a total loss from fire or wind comes entirely out of your own pocket.
Does my Mesa home insurance cover monsoon flooding?
Wind and hail damage from a monsoon storm is generally covered. Flooding from rising water is not, on any standard homeowners policy. NFIP reports that nearly one third of its 2014 through 2024 claims came from outside high risk flood zones, so a separate flood policy is worth pricing even if you are not in a mapped zone.
How much can I save bundling home and auto in Mesa?
Multi policy discounts generally run 10% to 25% when both policies sit with the same carrier. On the Mesa average home premium that is roughly $239 to $598 a year on the home side alone. The savings only hold if both the home and auto rates are competitive to begin with, which is why comparing carriers matters.
How often should I re shop my Mesa home insurance?
Once a year, at renewal. Arizona home premiums have moved sharply in recent years, carrier appetite for older roofs changes, and the company that was cheapest for your home three years ago often is not today. An annual comparison takes one conversation.
Get your Mesa home insurance quote today
If you own a home in Mesa and have not compared home insurance quotes in the last year, there is a real chance you are either overpaying or carrying limits that will not rebuild the house. The gap between the cheapest and most expensive carrier in this city runs well over a thousand dollars a year for identical coverage.
Riseson Insurance is an independent Arizona broker, which means we work for you and not for one carrier. We will pull quotes from multiple top rated companies, walk you through what is actually covered and what is not, and find the bundling angle that saves the most. Reach out for a free Mesa home insurance quote and see your options side by side.