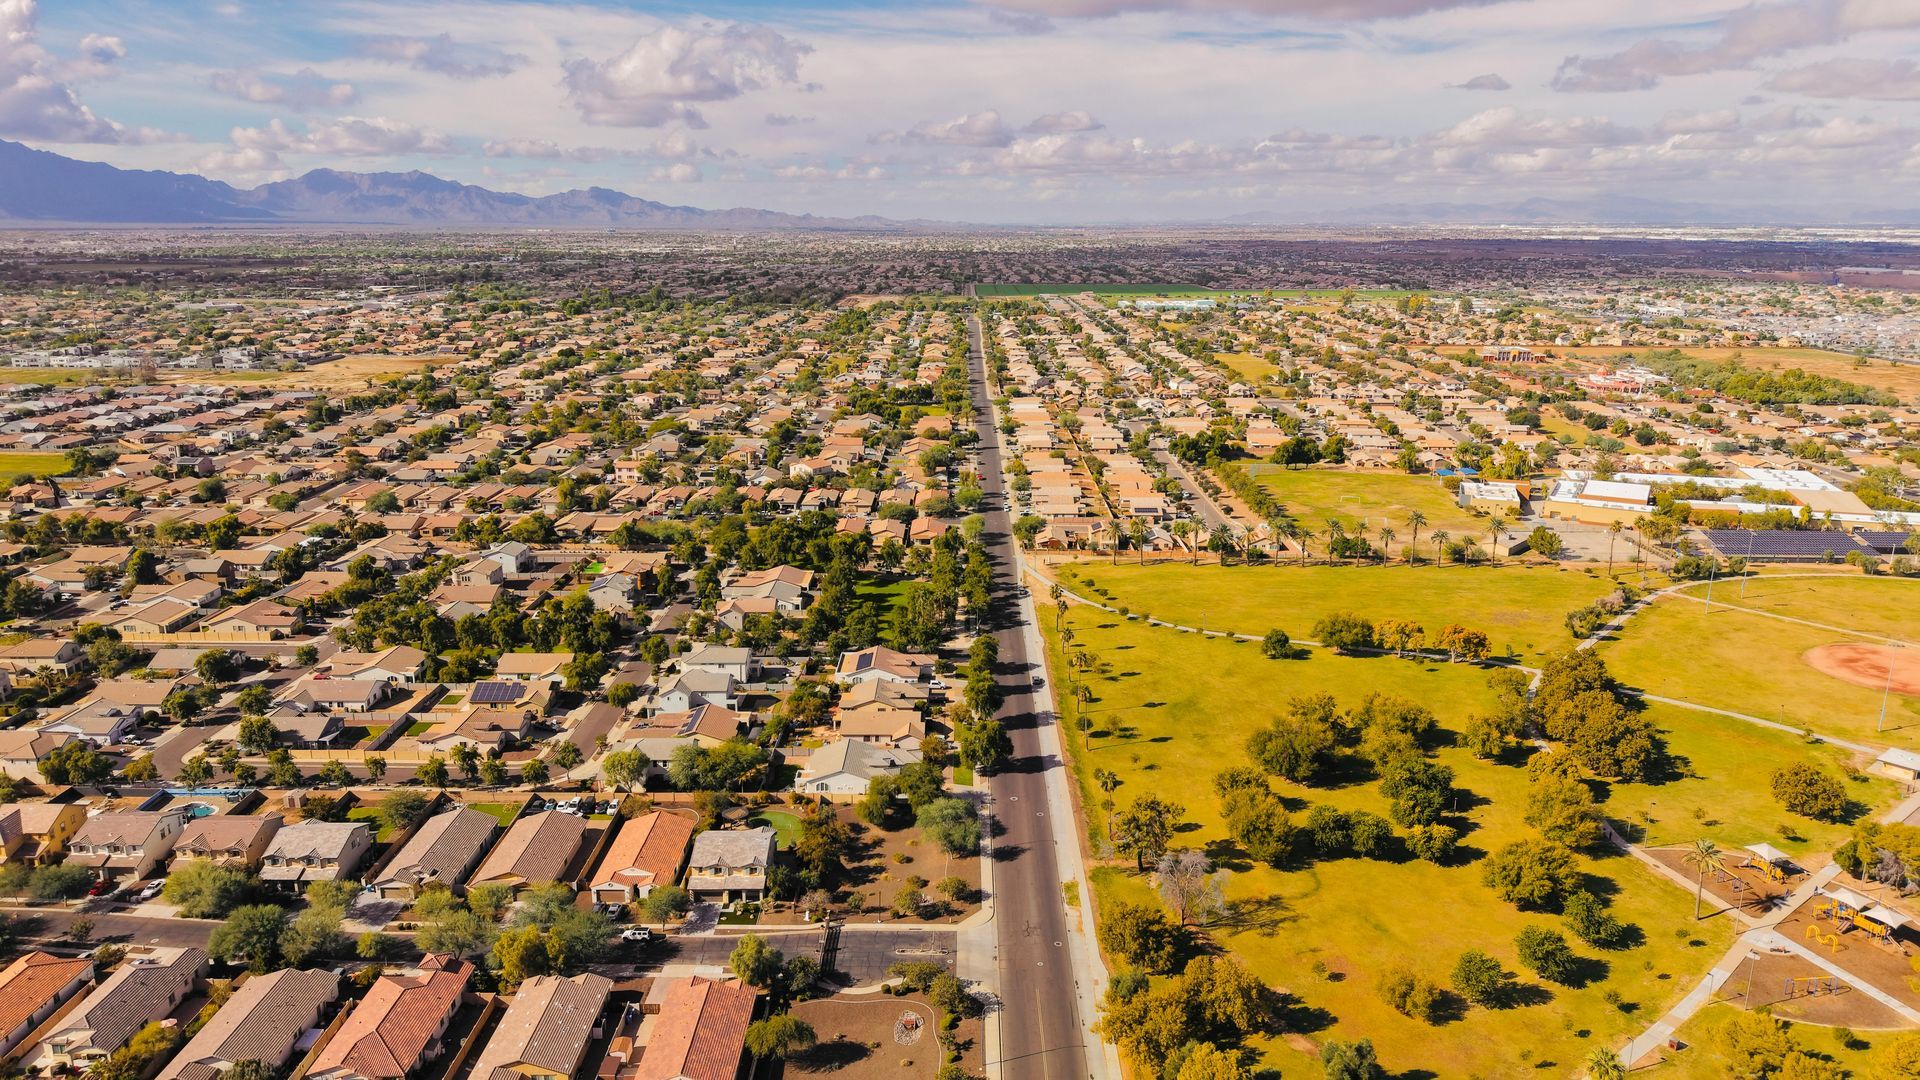
Gilbert has quietly become one of the most expensive places in the East Valley to insure a home. With Arizona home insurance rates up 62.1% over the past five years, the highest jump in the nation, even longtime Gilbert homeowners are seeing renewal letters that look nothing like what they signed up for.
If you live in Power Ranch, Seville, Val Vista Lakes, or anywhere inside the 85234, 85295, 85296, or 85297 zip codes, you are paying Arizona prices in a market that does not care that you have never filed a claim. Here is what Gilbert homeowners need to know about home insurance in 2026, and where the real savings hide.
Why Gilbert homeowners need solid home insurance
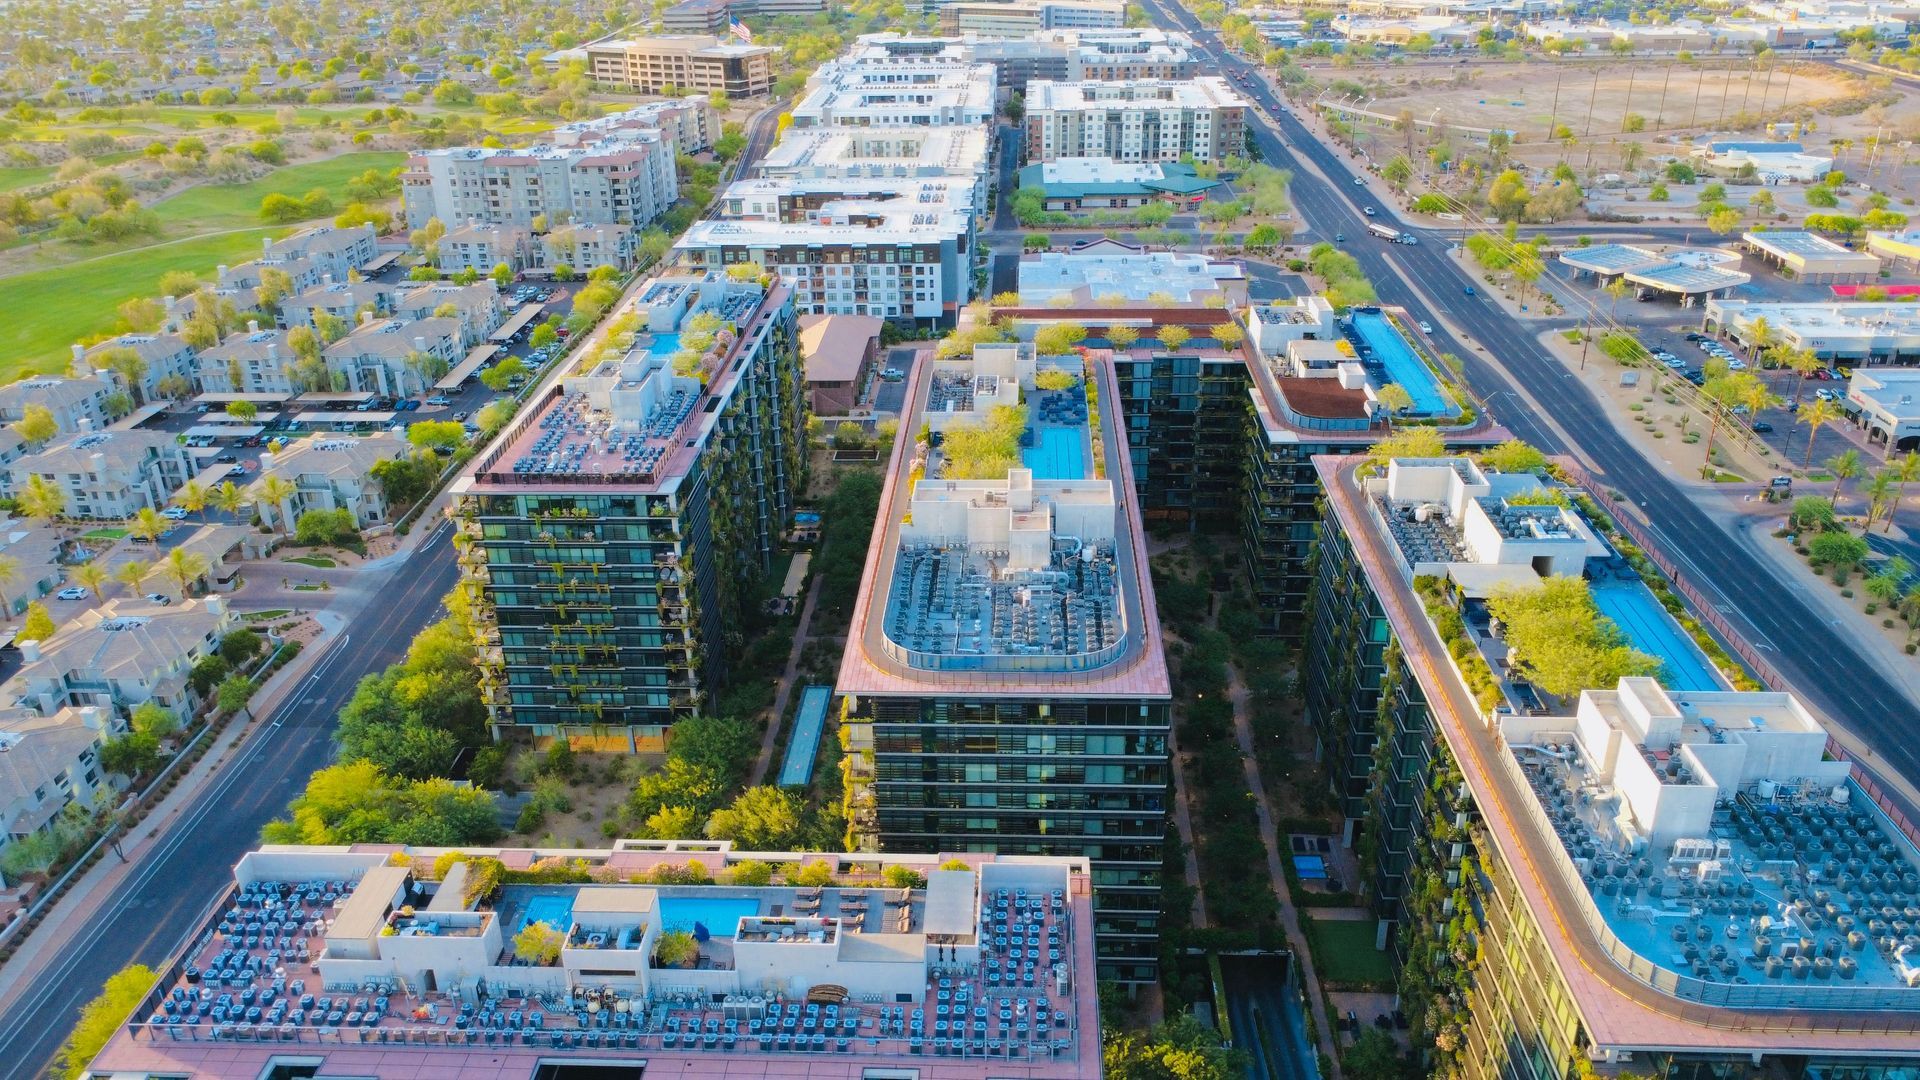
Gilbert is now the fifth-largest city in Arizona, with a population near 298,000 and still growing about 1.65% a year. That growth means newer stucco-on-frame construction, expensive replacement costs, and a lot of homes built close enough to share fences with strangers.
Home insurance in Gilbert is not legally required by the state, but if you have a mortgage your lender requires it. Even if your home is paid off, going without coverage is a gamble most Gilbert homeowners cannot afford. A standard HO-3 policy protects the dwelling, your personal belongings, liability if someone is hurt on your property, and additional living expenses if a covered loss makes the home unlivable.
How an independent broker like Riseson saves Gilbert homeowners money
Most homeowners get one quote from their auto carrier and stop there. Captive agents only sell one company's product, which means if that carrier raises rates, you are stuck or you start the shopping process from scratch.
Riseson Insurance is an independent broker, not a captive agency. That means we pull quotes from multiple top-rated carriers in one sitting, compare coverage line by line, and find the bundling angle, often home plus auto, that actually moves your premium. When a carrier files a rate increase in Arizona, we can move you to a better fit without you doing any of the legwork. For Gilbert homeowners specifically, this matters because rates and underwriting rules vary sharply between carriers across the East Valley.
What home insurance actually costs in Gilbert, AZ
The average annual home insurance premium in Gilbert is about $2,425 for a $300,000 dwelling, $100,000 in liability, and a $1,000 deductible, according to recent
Insure.com data. That puts Gilbert slightly below the Arizona state average, but well above the national mean.
Your actual rate in Gilbert depends on the home's age, roof condition and material, whether you have a pool, claims history in the last five to seven years, the credit-based insurance score, and the dwelling replacement cost. Newer Gilbert builds in Layton Lakes or Seville often get better roof discounts than 1990s homes in older parts of town. Bundling with auto can shave 10% to 25% off the home premium with most major carriers, and we routinely see Gilbert households save several hundred dollars a year just by switching to the right combination.
Arizona home insurance rules and Gilbert-specific risks
Arizona does not mandate home insurance, but the
Arizona Department of Insurance and Financial Institutions regulates every carrier writing policies in the state. That includes rate filings, claim handling timelines, and the rules around non-renewal notices, which Arizona requires 60 days in advance.
Gilbert-specific risks worth pricing in: monsoon-season haboobs and microbursts strip shingles and tear out fences, East Valley hail events have driven up roof claim costs, and interior plumbing leaks are the most common single claim in Arizona homes. Wildfire risk in Gilbert is lower than rural parts of the state, but carriers are increasingly using climate-risk models that price even low-risk Phoenix-metro zip codes higher than they did three years ago. Flood is excluded from every standard HO-3 policy. If you live near the Eastern Canal, Western Canal, or a low-lying retention basin, look at
NFIP flood insurance as a separate policy.
Beyond the basics: extra coverage Gilbert homeowners should consider
The standard policy is a starting point, not a finish line. Most Gilbert homeowners should also price out personal umbrella coverage (usually $200 to $400 a year for $1 million in extra liability), service line endorsements for water and sewer lines from the street to the house, equipment breakdown coverage for HVAC systems that work hard through Arizona summers, and scheduled personal property for jewelry, firearms, or electronics that exceed standard policy sublimits. If you rent out a casita or use part of the home for short-term stays, a standard HO-3 will not cover the rental activity. You need a landlord or short-term rental endorsement.
Frequently asked questions about home insurance in Gilbert, AZ
How much does home insurance cost in Gilbert, AZ?
The average is around $2,425 per year for $300,000 in dwelling coverage with a $1,000 deductible, based on Insure.com data. Your actual premium depends on the home's age, roof condition, claims history, and credit-based insurance score. Gilbert rates run slightly below the Arizona state average but well above the national mean.
Is home insurance required in Arizona?
Arizona does not legally require homeowners insurance, but every mortgage lender will require it as a condition of the loan. Even if your home is paid off, going uninsured is a serious financial risk given Arizona replacement costs and weather exposure.
Does home insurance cover monsoon and haboob damage?
Yes, standard HO-3 policies cover wind, hail, and falling-object damage, which includes most monsoon storm losses. Flooding from heavy rain is not covered and requires a separate NFIP policy. Damage to landscaping is usually capped at a small percentage of dwelling coverage.
Can I save by bundling home and auto in Gilbert?
Almost always. Most carriers offer 10% to 25% multi-policy discounts when you bundle home and auto, and as an
independent broker covering the East Valley, Riseson can pull bundled quotes from several carriers at once to compare side by side.
Why did my Gilbert home insurance go up so much?
Arizona has seen the largest five-year rate increase in the country at 62.1%, driven by rising construction costs, more severe weather, and updated climate-risk models. Industry forecasts call for roughly 8% additional increases in 2026 and another 8% in 2027, which is why shopping with an independent broker matters more than ever. For Phoenix-metro context, see our
Phoenix home insurance guide.
Get your Gilbert home insurance quote today
If you own a home in Gilbert and have not compared homeowners quotes in the last twelve months, you are likely overpaying, underinsured, or both. Riseson Insurance is an independent Arizona broker, which means we work for you, not for one carrier. We pull quotes from multiple top-rated companies, walk you through what is actually covered line by line, and find the bundling angle that saves the most. Reach out for a free Gilbert home insurance quote and see your real options in one place.