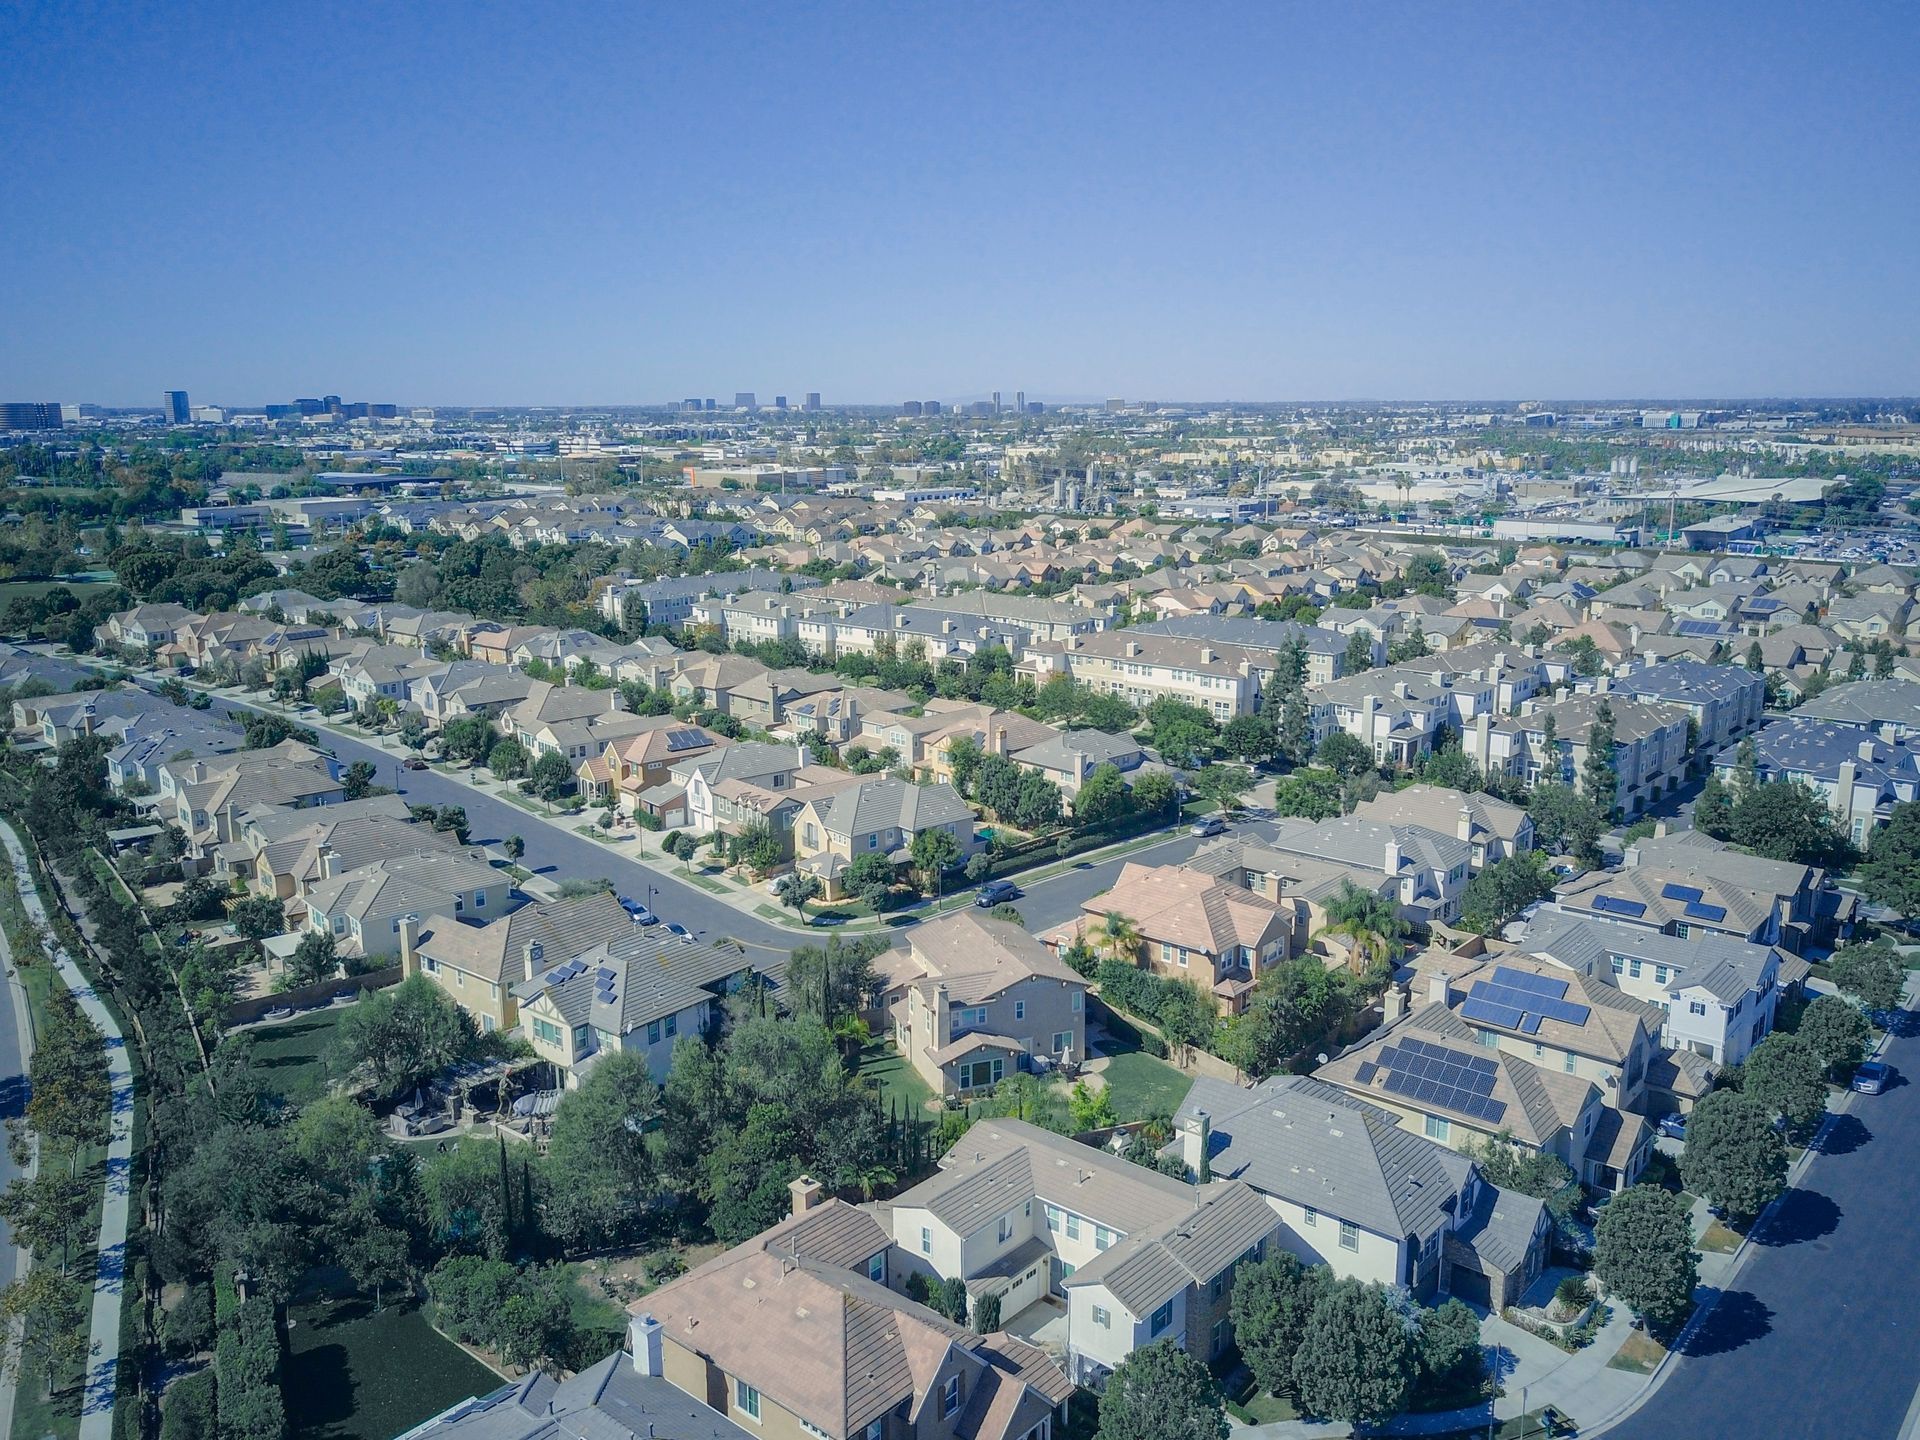
Surprise has gone from a small farming community on Grand Avenue to one of the fastest growing cities in Arizona, with a 2026 population of about 181,000 and growth of more than 25 percent since the 2020 census, according to
World Population Review. New rooftops keep spreading north along Loop 303 toward Asante and Marley Park, while Bell Road and US 60 carry the daily commute east toward Peoria, Glendale, and Phoenix.
All of that growth changes what you pay for car insurance in Surprise, AZ, and what happens when a claim goes wrong. Here is what West Valley drivers should understand about coverage, cost, and how to shop it without guessing.
Why Surprise drivers need more than Arizona's state minimum
Arizona requires every driver to carry at least 25/50/15 in liability coverage, meaning $25,000 in bodily injury coverage per person, $50,000 per accident, and $15,000 for property damage, according to the
Arizona Department of Insurance and Financial Institutions.
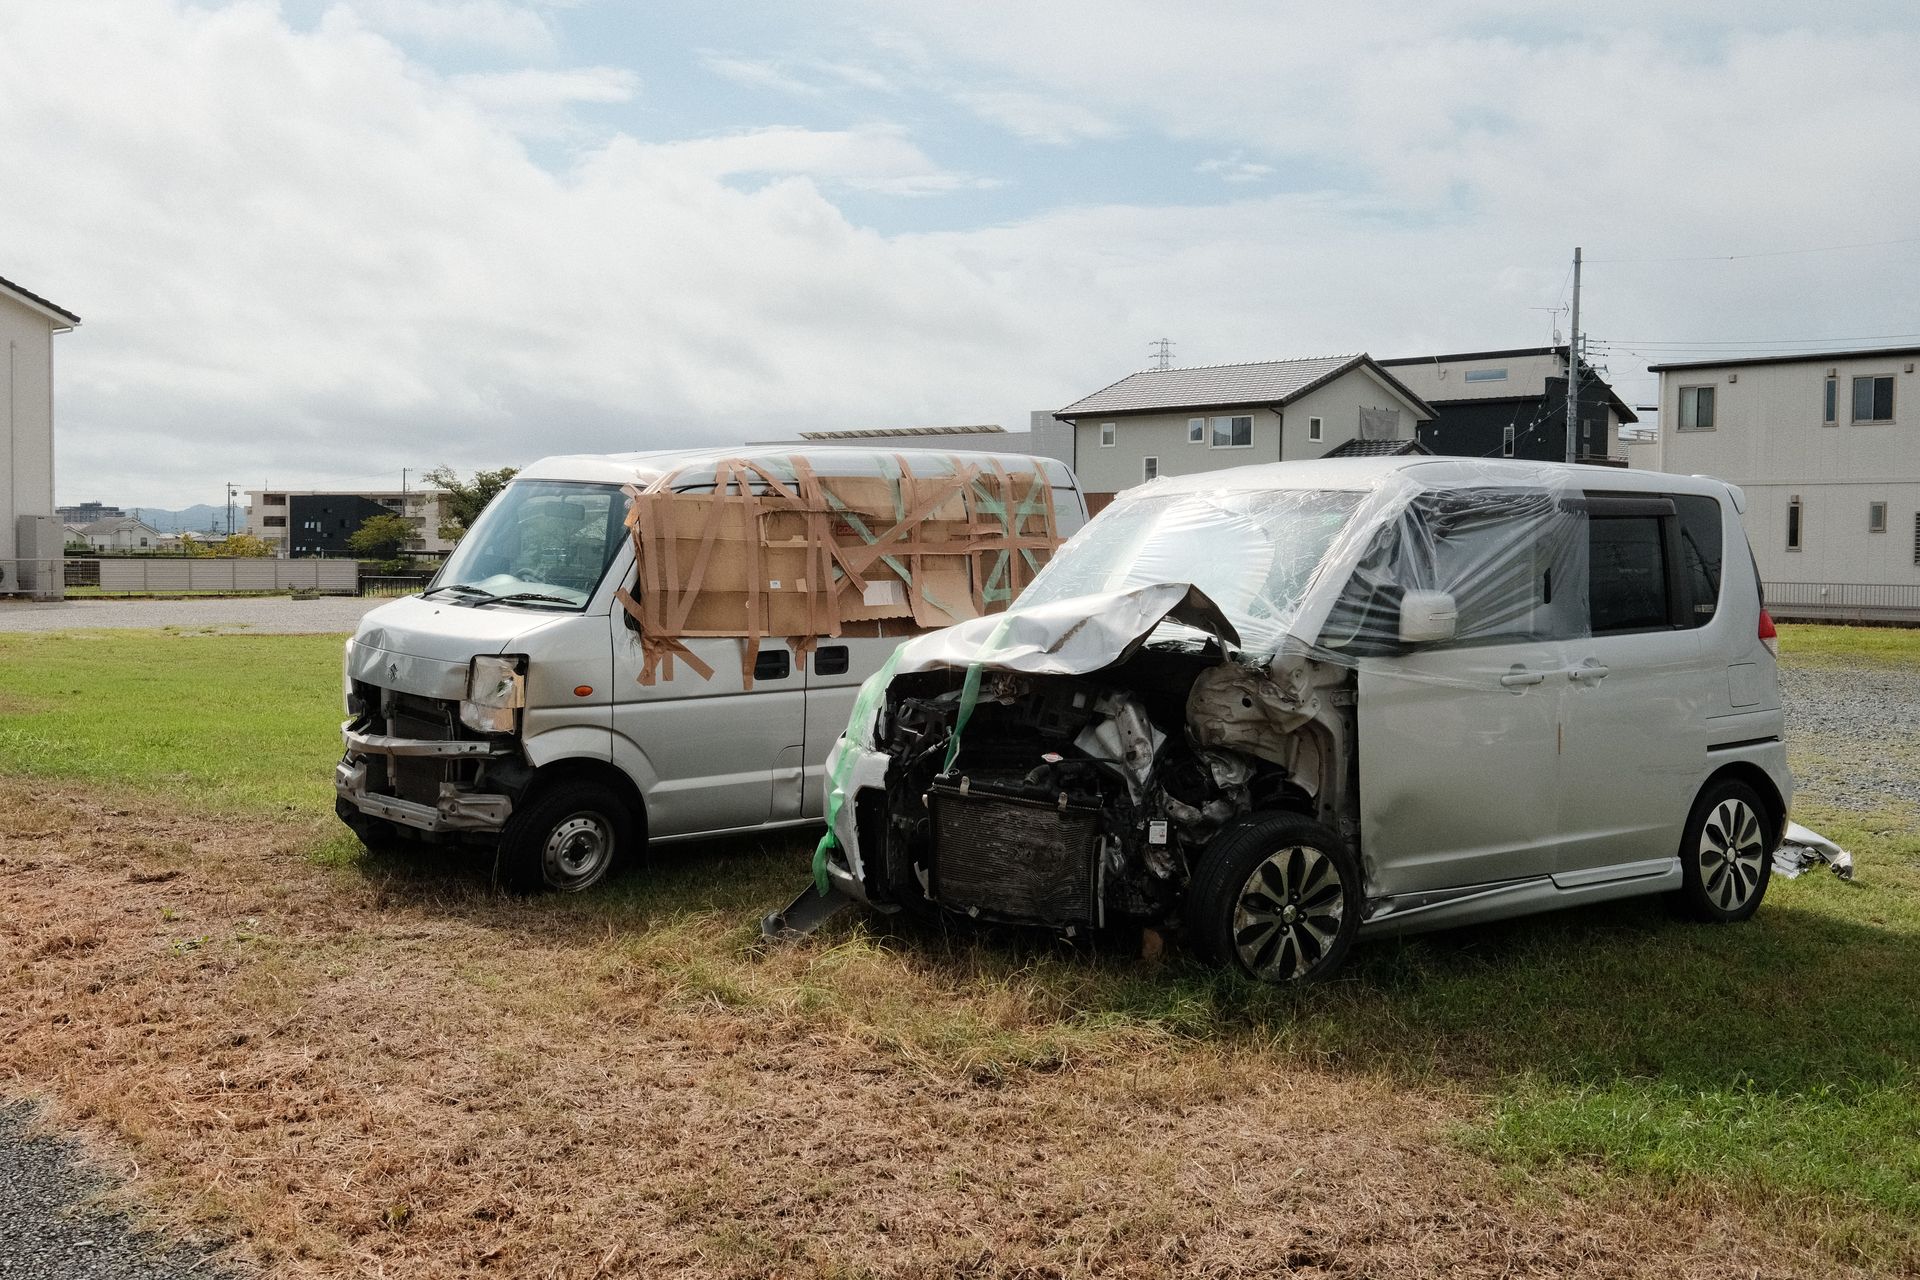
Those limits were written long before the average new truck or SUV crossed $50,000. A single at-fault collision at Bell Road and Litchfield Road involving two late-model vehicles can use up $15,000 of property damage coverage before anyone is treated for an injury. When the limit runs out, the balance is your personal responsibility, and Arizona is an at-fault state, so the driver who caused the crash owns the bill.
Most Surprise drivers we work with are better served by liability limits well above the legal floor. Raising limits from the minimum to something meaningful is usually one of the cheapest upgrades on the entire policy, especially for households with a home and savings to protect.
What car insurance actually costs in Surprise, AZ
The typical Surprise driver pays about $1,536 per year for car insurance, slightly more than the Arizona average of $1,470 and slightly less than the national average of $1,548, according to
The Zebra. Rates swing hard by age: teen drivers in Surprise average $6,385 per year, while drivers in their 50s average $1,368.
The cheapest full coverage rate available in Surprise runs about $51 per month for a clean-record sample driver, per
MoneyGeek, which also found that full coverage across Arizona costs roughly $42 per month more than a minimum policy. That gap is what buys collision and comprehensive coverage on your own vehicle.
Your record and your credit move the number more than your address does. The Zebra found a DUI adds about $792 per year in Surprise and a speeding ticket adds about $419, while moving from very poor to exceptional credit can cut the premium by roughly 64 percent. Two neighbors on the same street in Sun City Grand can pay very different rates for the same coverage.
The Surprise roads and risks that shape your premium
US 60, better known locally as Grand Avenue, runs diagonally through Surprise and crosses the city grid at odd angles, which creates long signal cycles and frequent serious crashes at intersections like Dysart Road and 163rd Avenue. Loop 303 has pulled much of the through traffic off Grand Avenue, but it has also made 70 mile per hour commuting the norm for families living in the newer subdivisions north of Waddell Road.
Surprise also has an unusual mix of drivers. Sun City West and Sun City Grand bring a large retiree population, spring training at Surprise Stadium fills the roads with out-of-state visitors every March, and Luke Air Force Base adds military families who move in and out on short notice. Insurers price all of that into local rates.
Then there is the Arizona baseline. Roughly 12 percent of Arizona drivers carry no insurance at all, according to
Insurance Information Institute data. That is close to one in eight vehicles around you on Loop 303, which is why uninsured and underinsured motorist coverage is not an optional extra in this market.
How an independent broker shops Surprise car insurance differently
A captive agent can only quote one company. If that company has raised rates in the 85374, 85379, 85387, or 85388 zip codes this year, you get the increase and a shrug. Riseson Insurance is an independent Arizona broker, so we quote the same driver across multiple top-rated carriers and show you the spread side by side.
That matters because carriers price Surprise differently. One company may love a retiree in Sun City Grand with low annual mileage and a garage. Another may price a young family in Marley Park with a teen driver far more competitively. We find the carrier that wants your specific household rather than forcing your household into one carrier's box.
We also review the policy line by line. Many of the Surprise drivers who call us have been carrying state minimum limits for years without realizing it, or have a $1,000 deductible they could not comfortably pay tomorrow. Fixing those gaps often costs less than people expect.
Bundling home and auto in the West Valley
Surprise is a homeowner city, and most of the households we insure own their home. Placing the home and the cars with the same carrier typically earns a multi-policy discount on both policies, and it simplifies claims when a monsoon storm damages both the roof and the car in the driveway on the same night. Our guide to
how much you save bundling home and auto in Arizona walks through the actual numbers.
If you already own in Surprise, our post on
home insurance in Surprise, AZ covers the property side, and pairing the two quotes is the fastest way to see your full household cost. Drivers who commute along the 101 will also find our
Peoria car insurance guide useful, since the same West Valley pricing factors apply.
Coverage beyond liability that Surprise drivers should consider
Uninsured and underinsured motorist coverage protects you when the other driver has nothing or not enough. Set it to match your own liability limits. Collision covers your car after an at-fault crash, and comprehensive covers theft, hail, and the monsoon flooding that turns low spots along Grand Avenue into ponds every August.
Rental reimbursement is worth a few dollars a month for anyone who cannot go without a car in a city where nothing is walkable. Roadside assistance earns its keep on summer days when a dead battery on Loop 303 at 112 degrees is a safety problem, not an inconvenience. For details on how vehicle values are settled after a total loss, see our guide to
replacement cost coverage for home and auto.
Frequently asked questions about car insurance in Surprise, AZ
How much does car insurance cost in Surprise, AZ? The typical Surprise driver pays about $1,536 per year, or roughly $128 per month, according to The Zebra. The cheapest full coverage rate in the city runs about $51 per month for a clean-record sample driver per MoneyGeek. Your age, record, credit, and vehicle move the number well above or below those figures.
What is the minimum car insurance required in Arizona? Arizona requires 25/50/15 liability coverage: $25,000 bodily injury per person, $50,000 per accident, and $15,000 property damage per accident, per the Arizona Department of Insurance and Financial Institutions. Uninsured motorist coverage is not required, but carriers must offer it and most Surprise drivers should take it.
Does bundling home and auto save money in Surprise? Yes. Most carriers apply a multi-policy discount to both the home and the auto policy when they are written together, and Surprise is a homeowner city, so the bundle applies to most households. An independent broker can quote the bundle across several carriers to find the largest combined discount.
Why is car insurance more expensive in Surprise than the Arizona average? Surprise averages $1,536 per year against $1,470 statewide, per The Zebra. Fast population growth, heavy commuter traffic on Grand Avenue and Loop 303, a large seasonal and retiree driver mix, and Arizona's roughly 12 percent uninsured driver rate all feed into local pricing.
Do I need extra coverage for monsoon season in Surprise? Comprehensive coverage is what pays for flood, hail, and wind damage to your vehicle, and it is not included in a liability-only policy. If your car is worth more than a few thousand dollars, comprehensive is inexpensive protection during the July through September monsoon.
Get your Surprise car insurance quote today
If you live in Surprise and have not compared car insurance quotes in the last year, you are likely overpaying or underinsured. Riseson Insurance is an independent Arizona broker, which means we work for you, not for one carrier. We will pull quotes from multiple top-rated companies, walk you through what is actually covered, and find the bundling angle that saves the most. Reach out for a free Surprise car insurance quote and see your options in one place.