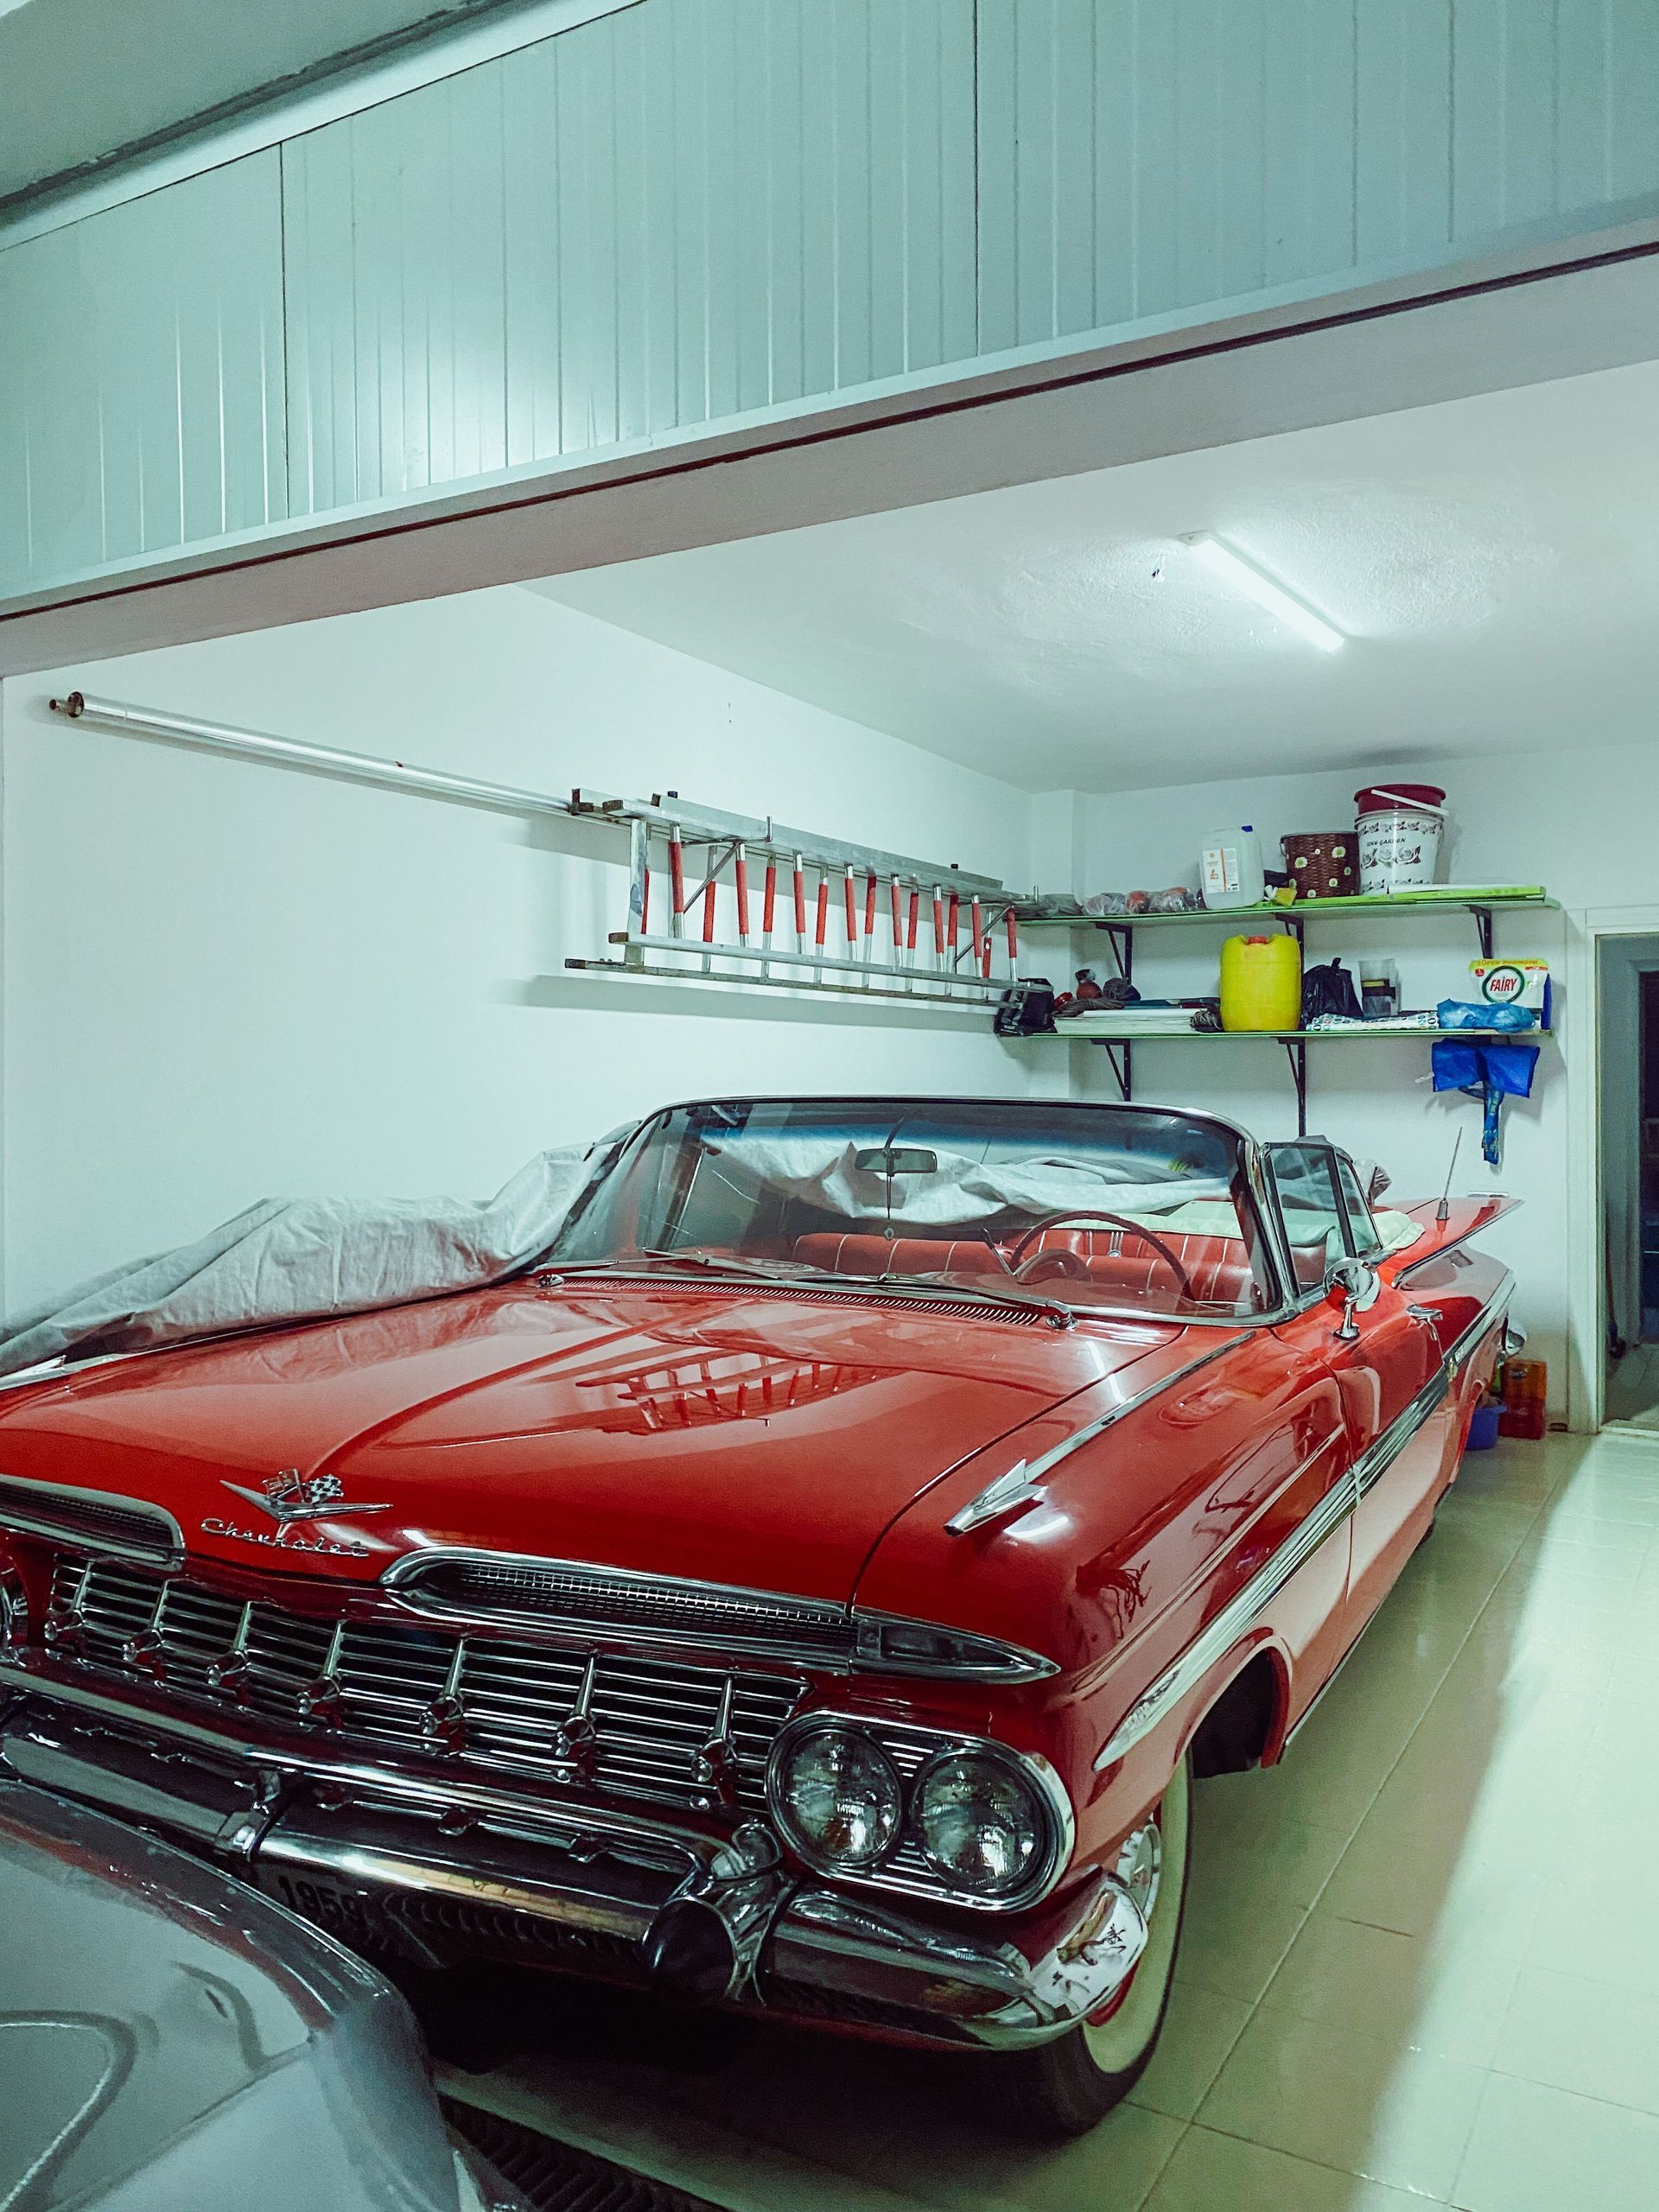
If you own a classic car, a motorhome, a boat, or any vehicle that does not lose value the way a daily commuter does, a standard auto policy can leave you badly shortchanged after a total loss. Most policies pay actual cash value, which means the insurer subtracts depreciation and hands you a check based on what the vehicle is worth today, not what it means to you or what you put into it. For a restored 1969 Camaro or a low-mileage Airstream, that gap can run into tens of thousands of dollars.
Agreed value insurance solves that problem. You and the insurer settle on a set dollar figure up front, write it into the policy, and that is the amount you collect if the vehicle is totaled or stolen. As an independent Arizona broker, Riseson Insurance helps owners across the state get agreed value coverage that actually reflects what their vehicle is worth.
Why agreed value insurance matters for Arizona owners
The core difference is depreciation. Actual cash value coverage factors in age, mileage, and condition, then reduces your payout accordingly. Agreed value insurance removes depreciation from the equation entirely, so a covered total loss pays the full agreed figure minus your deductible, with no post-loss haggling over what the vehicle was really worth.
That matters most for vehicles whose value is unusual or rising. Classic and collector cars often appreciate rather than depreciate, and the values of RVs and boats can swing widely from what a pricing guide shows. According to
Progressive, agreed value coverage is designed for exactly these situations, where a standard depreciated payout would never make the owner whole.
How Riseson helps as an independent broker
Not every carrier offers agreed value coverage, and the ones that do set very different rules on eligibility, mileage, storage, and appraisals. That is where working with an independent broker pays off. Riseson is not tied to one company, so we shop multiple top-rated specialty and standard carriers to find the one that will write your vehicle at a fair agreed figure.
We also look at the whole picture. Many Arizona owners keep a collector car alongside a daily driver, a home, and sometimes an RV or boat. Bundling those policies under carriers that play well together often lowers your total cost and closes coverage gaps. If you already carry
car insurance with us in the Valley, adding agreed value coverage for a specialty vehicle is straightforward.
What agreed value coverage costs and what to expect
Agreed value policies can cost more than a basic depreciated policy, but for collector and specialty vehicles they are frequently cheaper than you expect, because these vehicles are driven less and stored carefully. Premiums depend on the agreed figure, your driving record, where the vehicle is garaged, and annual mileage.
Most carriers require a professional appraisal or documentation to set the agreed value. A certified appraisal typically runs between 100 and 300 dollars and gives you solid proof of value that protects you at claim time.
Bankrate notes that agreed value coverage tends to come with limited provider options, which is another reason to let a broker do the shopping rather than calling carriers one at a time.
Arizona requirements and qualifying for agreed value
Agreed value is a coverage type, not a replacement for the liability the state requires. Every registered vehicle in Arizona still needs at least 25,000 dollars per person and 50,000 dollars per accident in bodily injury liability plus 15,000 dollars in property damage, per the
Arizona Department of Insurance and Financial Institutions. Agreed value sits on top of that as your physical damage protection.
To qualify for agreed value on a classic or collector vehicle, carriers generally want the vehicle to be roughly 20 to 25 years old, garaged in a locked enclosed structure, driven on a limited basis rather than as a daily commuter, and kept under an annual mileage cap that often falls between 2,500 and 5,000 miles. RVs, motorhomes, and boats follow similar logic, with the agreed figure set by appraisal or documented purchase price.
Beyond the basics for complete protection
Agreed value handles the headline number, but a strong specialty policy includes more. Look for coverage that protects spare parts and tools, pays toward a professional restoration rather than a generic repair, and offers flexible usage so you can take the vehicle to shows and club events without losing protection. Some policies even waive the deductible on a total loss.
It also pays to coordinate your coverage. An RV parked at home, a boat on an Arizona lake, and a collector car in the garage all interact with your
RV insurance and
boat insurance decisions. Reviewing them together prevents the overlaps and blind spots that show up when each policy is bought in isolation.
Frequently asked questions about agreed value insurance
What is agreed value insurance? Agreed value insurance is coverage where you and your insurer agree on a set dollar value for the vehicle up front and write it into the policy. If the vehicle is totaled or stolen, you receive that full agreed amount minus your deductible, with no depreciation subtracted.
How is agreed value different from actual cash value? Actual cash value pays what the vehicle is worth at the time of loss after depreciation, which usually means a lower check. Agreed value ignores depreciation and pays the figure you settled on when the policy was written.
Do I need an appraisal for agreed value coverage in Arizona? Most carriers require a professional appraisal or strong documentation to set the agreed figure. A certified appraisal generally costs 100 to 300 dollars and supports your payout if you ever file a claim.
Can I get agreed value coverage on an RV or boat? Yes. Agreed value is commonly used for motorhomes, travel trailers, and boats, where standard pricing guides often understate real value. The agreed figure is set by appraisal or documented purchase price.
Get your agreed value quote today
If you own a classic car, RV, motorhome, or boat in Arizona and you are still relying on an actual cash value policy, you are likely one bad day away from a payout that does not come close to what your vehicle is worth. Riseson Insurance is an independent Arizona broker, which means we work for you, not for one carrier. We will compare agreed value options from multiple top-rated companies, explain exactly what is covered, and find the bundling angle that saves the most. Reach out for a free agreed value quote and see your options in one place.