Every month you write a check for car insurance, and most of that price is based on averages: your age, your ZIP code, the kind of car you drive. Telematics flips that model. Instead of guessing what kind of driver you are, your insurer measures it, and if you drive well, you get rewarded for it.
For safe Arizona drivers, a telematics program can be one of the fastest ways to cut a premium without dropping coverage. As an independent broker, Riseson Insurance can help you find the carrier and the program that actually fits how you drive.
What telematics auto insurance actually is
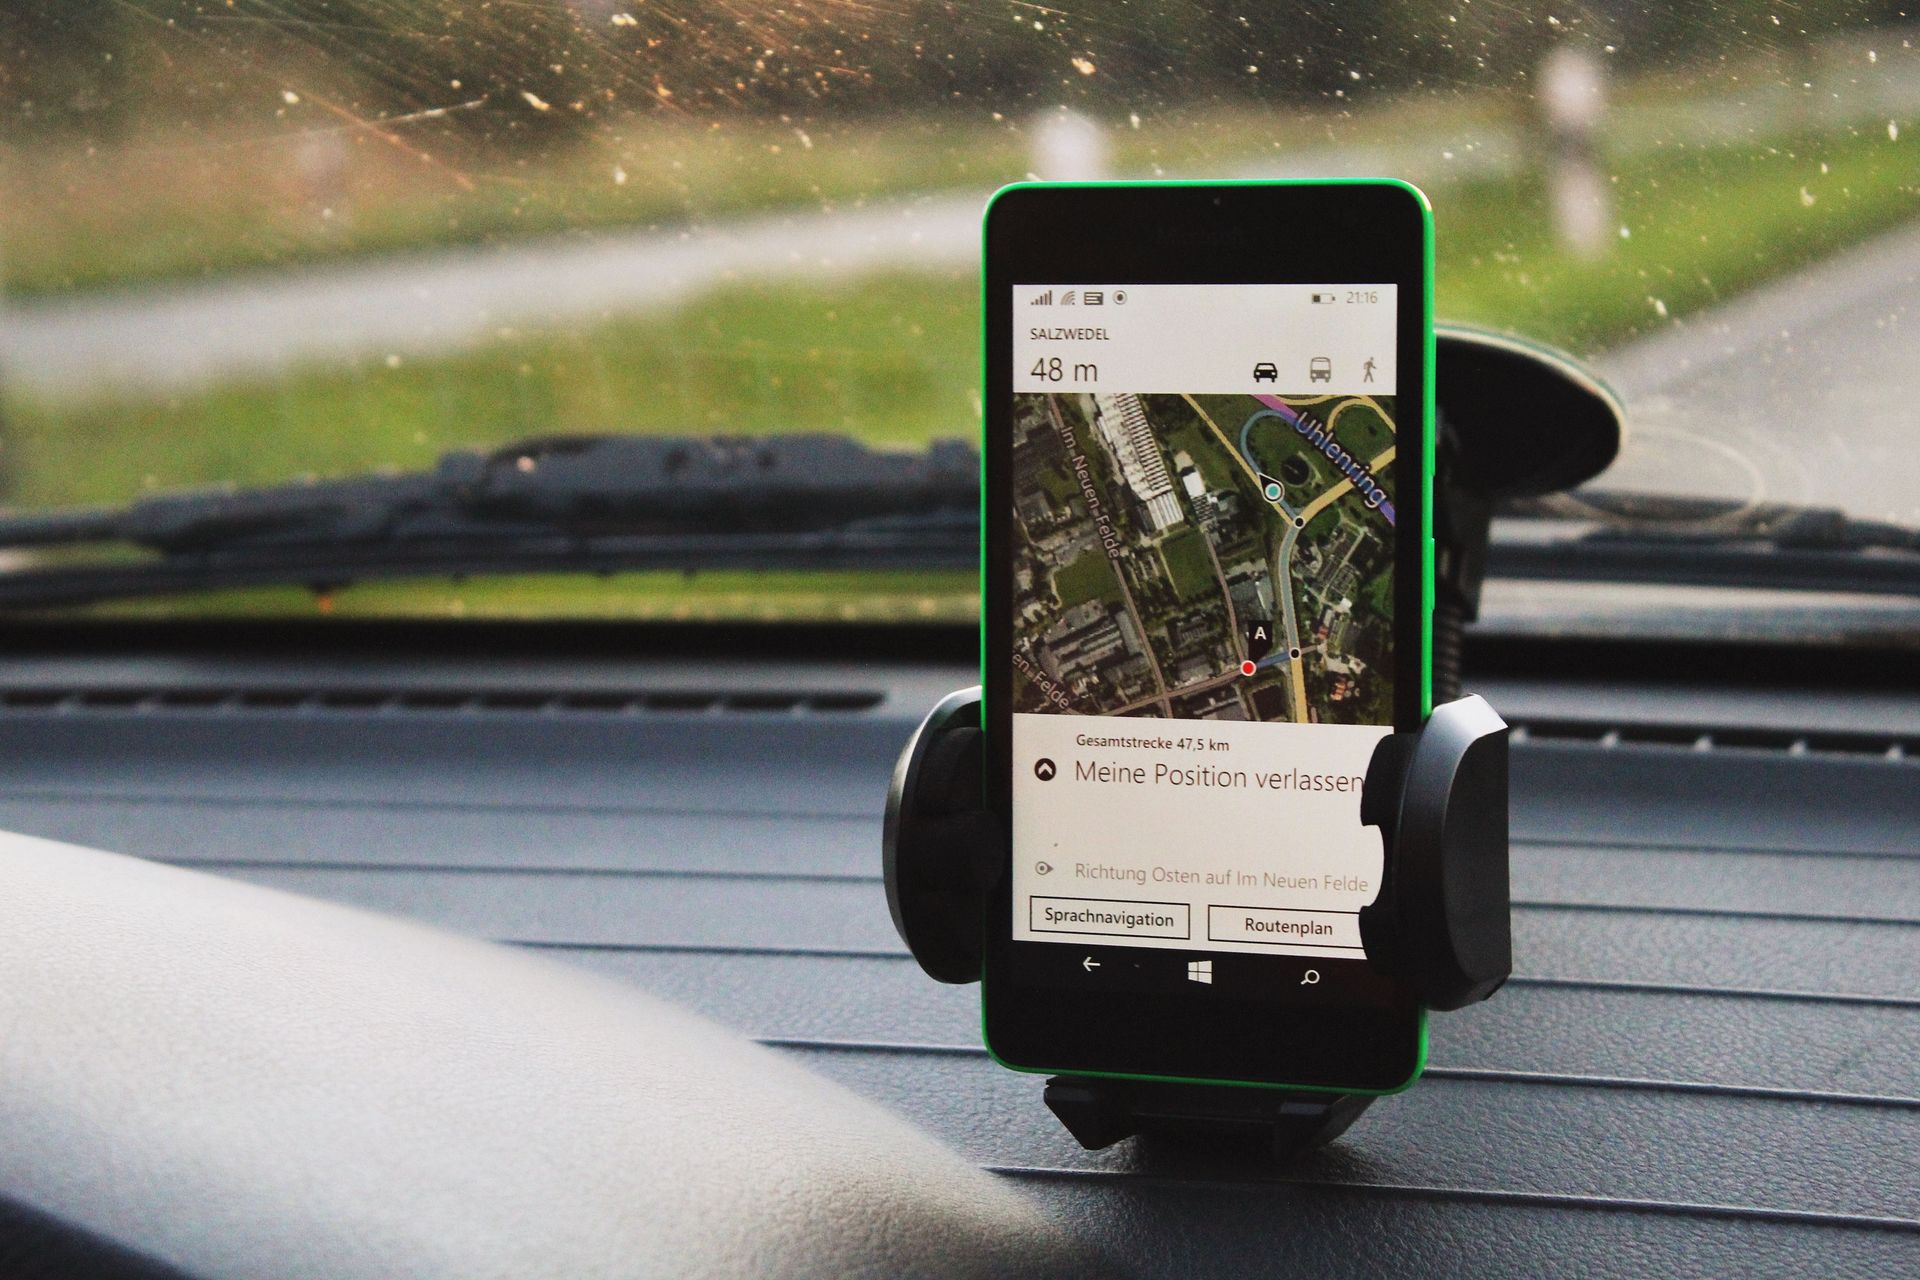
Telematics, also called usage-based insurance, uses a smartphone app or a small plug-in device to record how you drive. It looks at things like your speed, how hard you brake, rapid acceleration, the time of day you are on the road, and how much you handle your phone behind the wheel.
After a monitoring period that usually runs 90 days to six months, the carrier scores your driving and sets a discount at renewal. According to the
Insurance Information Institute, usage-based programs have moved from a novelty to a mainstream option offered by most major carriers.
How much Arizona drivers can save
Savings vary widely because they depend on your actual driving, not a flat rate. Many programs start with an enrollment discount just for signing up, then apply a larger renewal discount once your safe-driving data is in. Careful drivers commonly land in the 10 to 30 percent range.
The results are not automatic, though.
Consumer Reports notes that the typical telematics user sees a more modest annual savings, and drivers with a young person on the policy tend to save the most. The upside is largest for households that genuinely drive safely and want their premium to reflect it.
The programs you will see in Arizona
Most national carriers that write policies in Arizona offer a telematics option under their own brand name. You will run into programs like Progressive Snapshot, GEICO DriveEasy, Travelers IntelliDrive, Allstate Drivewise, and Nationwide SmartRide, among others.
They are not all built the same. Some are discount-only, meaning the worst case is simply that you do not earn a discount. Others can raise your rate if your driving scores poorly during the monitoring window. Knowing which is which before you enroll matters, and that is exactly the kind of detail an independent broker sorts out for you.
The privacy trade-off worth understanding
Telematics works by collecting data, so it is fair to ask where that data goes. Programs track location, time of day, and driving behavior, and policies differ on how that information is stored and used.
The
Consumer Federation of America encourages drivers to read the program terms before enrolling so they know what is being measured. For most safe drivers the discount is worth it, but you should go in with clear expectations rather than surprises.
Arizona requirements still apply
A telematics discount lowers your price, but it does not change what the state requires you to carry. Arizona law sets a minimum of 25/50/15: 25,000 dollars in bodily injury per person, 50,000 dollars per accident, and 15,000 dollars in property damage, per the
Arizona Department of Insurance and Financial Institutions.
Arizona is an at-fault state, and roughly one in eight drivers on the road is uninsured. Those two facts are why many drivers carry more than the minimum. A telematics discount can help you afford higher limits and uninsured motorist coverage rather than settling for the bare legal floor.
Which Arizona drivers benefit most
Telematics rewards low-risk driving, so the biggest winners are the people who already drive that way. If your commute is short, you avoid late-night trips, and you rarely slam the brakes, a usage-based program is likely to pay off quickly.
It is also worth a close look for retirees and remote workers who drive fewer miles, and for families paying steep premiums on a teen driver. On the other side, if you spend long stretches in stop-and-go Phoenix rush-hour traffic or drive a lot of high-speed freeway miles, compare a discount-only program first so a rough score cannot raise your rate. Reviewing the program details is where an independent broker earns their keep.
Frequently asked questions
Does telematics raise my rate if I brake hard once? A single event will not sink your score. Programs look at patterns over the whole monitoring period, so consistent safe driving is what counts. With discount-only programs, a rough month at worst means no discount rather than a surcharge.
Do I have to keep the app installed forever? Most programs only monitor during an initial period, then lock in your discount. A few continuous programs keep scoring you, which can work in your favor if you keep driving well. Ask which type you are enrolling in.
Is telematics a good fit for young drivers in Arizona? Often yes. Young drivers pay the highest premiums, so a safe-driving discount has the most room to help. Households adding a teen driver frequently see the biggest dollar savings from these programs.
Can an independent broker help me choose a program? Yes. That is the advantage of working with Riseson Insurance. We compare telematics options across multiple carriers so you get the discount structure that fits your driving instead of whatever one company happens to sell.
Find the right telematics program for your driving
If you drive carefully and have not looked at a usage-based option, you may be leaving real money on the table every renewal. Riseson Insurance is an independent Arizona broker, which means we work for you, not for one carrier. We will compare telematics programs from multiple top-rated companies, explain how each one measures your driving, and pair the discount with the coverage limits that keep you protected on Arizona roads. Reach out for a free quote and see your options side by side. You can also explore more ways to save in our guides on
lowering your car insurance,
safe driver discounts, and
driving less to cut costs.